Public adjuster in Elk Grove, CA for denied or underpaid claims
Accurate Claims Consulting works as licensed public adjusters for Elk Grove homeowners and business owners. We document the loss independently, interpret the policy language and negotiate with the insurance company for you. You pay nothing up front: we only get paid when your insurance company pays the claim.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › Elk Grove
Elk Grove homes and businesses we help
Elk Grove grew fast, and much of its housing dates from the last three decades: stucco exteriors, concrete tile or composition roofs, slab foundations, and tightly spaced lots. Newer construction does not mean fewer claims. It means different ones, and carriers are quick to blame builder defect for damage that a policy actually covers.
- Owners of newer stucco, tile-roof and slab-foundation homes in Elk Grove’s subdivisions
- Households near Laguna Creek and its tributaries, which rise quickly in atmospheric river storms
- Owners of homes and businesses along the open southern and eastern edges of the city, where grass fires burn each dry season
Whether your Elk Grove claim was just reported, is stalled, was underpaid or has been denied, we can take it from where it stands.
Client feedback and settled claims


He was very responsive all the time even after business hours, not to mention the unbelievable settlement he fought for us
Leslie Harding, Google review
- Slab leak, North Hollywood, CA (February 2022). A slab leak flooded the downstairs living room and several other rooms. The insurer gave $3,000 for repairs; we secured an additional $110,000 for repairs, contents and additional living expenses. North Hollywood slab leak case
- Electrical house fire, Los Angeles, CA (October 2021). The insurer tried to deny the claim, calling it arson. Accurate submitted evidence proving the fire was accidental and secured a $250,000 settlement. Los Angeles electrical fire case
Our adjusters worked for major insurance companies like Farmers, State Farm and Allstate before they began representing Elk Grove policyholders. See recent projects and client reviews.
Elk Grove hazard and drainage facts
Elk Grove’s own planning documents show where flood, levee and fire risk sit for a property owner here.
Four hazards rated high for Elk Grove
The City of Elk Grove annex to the 2021 Sacramento County Local Hazard Mitigation Plan rates four hazards as high significance: flood (1% and 0.2% annual chance), levee failure, wildfire and dam failure. Extreme heat, heavy rains and storms, drought and earthquake are rated medium (Sacramento County LHMP 2021, Annex B: City of Elk Grove).
About 1,266 acres in the 100-year flood zone
The same annex counts about 1,266 acres of the city inside the 1% annual chance floodplain, 477 of them improved (developed) acres (Annex B, Table B-25). If your parcel is one of them, a lender may require flood insurance, because the homeowners policy excludes rising water.
400 miles of storm pipe and 13 watersheds
The Storm Drainage Master Plan the city adopted in 2011 covers about 400 miles of underground pipe and 60 miles of natural and constructed channels across 13 watersheds, including Laguna Creek, Elk Grove Creek and Deer Creek (City of Elk Grove, Storm Drainage Master Plan). When that system backs up, the policy wording on surface water and sewer backup decides the claim.

Water damage claims in Elk Grove
Flat terrain and heavy winter rain leave water standing where it cannot drain, and Laguna Creek and its tributaries rise quickly during atmospheric river events. Inside the home, supply line fittings, water heaters, and appliance connections can fail without warning on a slab.
Our Expertise: On slab construction water travels under flooring and into base plates and wall cavities. We use moisture mapping to define the real boundary of the loss instead of guessing at it.
The Hidden Risk: A carrier may argue that a leak was gradual, or that the failure was a construction defect outside the policy. Both positions are answerable, but only with evidence collected before repairs begin.

Storm and wind damage claims in Elk Grove
Valley wind events cross open ground with nothing to slow them, and they hit newer subdivisions where rooflines are complex and fences are long. Concrete tile cracks, ridge and hip pieces shift, and composition shingles lift at the edges.
The Accurate Advantage: Tile roofs conceal damage well. Broken tiles and torn underlayment often look fine from the ground, so we inspect the assembly directly and document every plane.
Wind and Rain Impact: Once underlayment is compromised, water reaches the sheathing and eventually the ceiling. Recording the storm date and the damage sequence keeps it all inside one claim.
Fire damage claims in Elk Grove
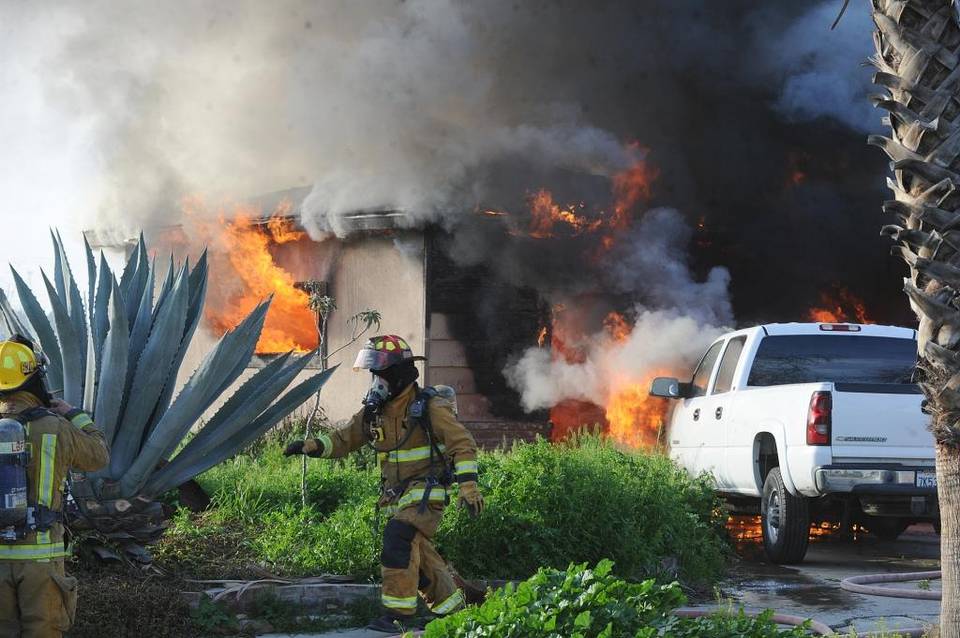
In dense modern subdivisions, a fire that starts in a garage or attic can involve neighboring structures within minutes. Even a contained fire leaves smoke and heat damage through an open floor plan and a shared attic space.
What We Do: We inventory contents thoroughly, work with specialists to identify heat-affected trusses, wiring, and HVAC components, and pursue the additional living expense coverage your policy provides.
Code Compliance: Repairs must comply with the current California Building Standards Code and City of Elk Grove permitting. Even newer homes can face upgrade requirements at the time of rebuild, and Ordinance or Law coverage is what pays for them.
Wildfire and smoke damage claims in Elk Grove
Elk Grove sits on the valley floor rather than in the hills, but the open grassland and agricultural land along its southern and eastern edges carry fast-moving grass fires every dry season, and smoke from foothill and coastal range fires settles across the entire Sacramento Valley.
Smoke and Ash Are Real Damage: Modern homes run their air handlers constantly through valley summers, drawing ash into ductwork, filters, and insulation. That contamination is documentable and payable when it is treated as damage rather than dust.
Grass Fire Exposure: Radiant heat from a passing grass fire warps vinyl fencing, melts irrigation, damages siding and window seals, and scorches roof edges without ever igniting the structure.
Why Elk Grove owners work with Accurate Claims Consulting
- Local Cost Insight: We price repairs using current regional labor and material costs rather than the dated averages sitting inside carrier estimating software.
- Expert Negotiation: We understand how a scope gets narrowed and how to reopen it with documentation.
- Contingency-Based Service: The inspection and the policy review are free, and our fee comes only from what we recover for you.
- Full Claim Management: We prepare the Proof of Loss, handle supplements, and keep every policy deadline on track.
How an Elk Grove claim moves forward
- Inspect and document. We map moisture under slab flooring and into wall cavities, inspect tile and underlayment plane by plane, and record smoke drawn into the HVAC system.
- Estimate and file. We price the work at Sacramento County rates, including City of Elk Grove permit and code items, and submit the claim with full support.
- Negotiate and settle. We take every carrier question and push the claim to a paid settlement. We only get paid when your insurance company pays the claim.
Every public adjuster in California needs a license from the California Department of Insurance, which also runs a consumer help line for claim problems. The National Association of Public Insurance Adjusters (NAPIA) publishes industry resources on how the work is done.
Claims we handle for Elk Grove properties
Start with the claim type closest to your Elk Grove loss; each page explains what to photograph, keep and send.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
More cities near Elk Grove
Elk Grove is part of our Northern California coverage, which also reaches Roseville, Concord, Vallejo, Hayward, Sunnyvale and Redding. See the Northern California page for every location.
Elk Grove claim questions
Is my Elk Grove property in a flood zone?
It may be. The city’s hazard plan annex puts about 1,266 acres of Elk Grove inside the 1% annual chance floodplain. Elk Grove Public Works can tell you the FEMA flood zone for your parcel; either way, rising water needs a separate flood policy.
My home is newer. Can the insurer deny a claim as a construction defect?
They can raise it. Many policies exclude the defect itself while still covering the damage it caused. Establishing what failed and what that failure damaged is how these claims get resolved.
Does my policy cover cracked roof tiles after a windstorm?
Wind damage is generally covered, but a carrier may attribute cracked tile to age or foot traffic. Dated photographs, storm records and an inspection of the underlayment are what separate the two explanations.
Do I need repair bids before I call a public adjuster?
No. We write our own detailed estimate as part of the claim. Contractor bids can support it, but they are rarely written in the format an insurer accepts as a scope of loss.
Talk to an Elk Grove public adjuster
Get the claim settlement you deserve. A failed supply line on a slab, cracked tile after a wind event, or ash through the HVAC system after a grass fire all deserve a proper evaluation before you accept a settlement figure.
Call us today or complete the form for a free, no-obligation claim inspection in Elk Grove. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.