Public adjuster in Roseville, CA for denied or underpaid claims
Accurate Claims Consulting serves Roseville property owners as licensed public adjusters. We handle the inspection, the loss documentation, the estimate and the negotiation, so the settlement reflects the real cost of repair rather than a desk review. Our fee is contingent: we only get paid when your insurance company pays the claim.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › Roseville
Roseville owners we work for
Roseville pairs an older core near the historic rail yard with a large volume of subdivision housing built from the 1990s onward, spreading east toward the Placer County foothills. Newer stucco and tile construction fails differently than the bungalows downtown, and insurance carriers apply very different assumptions to each.
- Owners of older bungalows in the downtown core near the historic rail yard
- Homeowners in the stucco and tile-roof subdivisions built from the 1990s onward
- Property owners on the eastern edge of Roseville, toward the foothills, and along Dry Creek, Cirby Creek and Linda Creek
A Roseville claim can come to us at any point: just filed, stuck in review, paid short or denied.
Reviews and claim results for property owners


Great service to us at a most difficult time. I highly recommend him for Any insurance claim representation.
Jim Jackson, Google review
- Slab leak, San Diego, CA (February 2021). The leak caused water and foundation damage, and the insurer initially denied the claim as a long-term leak. Accurate reopened the claim and secured a $247,000 settlement. San Diego slab leak case
- Attic fire, San Diego, CA (March 2022). The fire started in the attic. The insurer offered $92,000 and Accurate secured a $311,000 settlement. San Diego attic fire case
Before they represented Roseville policyholders, our adjusters evaluated claims for Farmers, State Farm and Allstate. More on our recent projects and reviews pages.
Roseville flood history and planning
Roseville has measured its floods closely, and the numbers below come straight from the city.
Hazard plan updated in November 2023
The Roseville City Council adopted the current update of the city’s Multi-Hazard Mitigation Plan on November 15, 2023; the original plan dates from July 2005 (City of Roseville, Multi-Hazard Mitigation Plan).
The January 10, 1995 flood
On January 10, 1995 several creeks flooded at once. The city recorded high water at 132.74 feet above sea level on Dry Creek at Riverside Avenue, 138.63 feet on Cirby Creek at Tina Way and 159.56 feet on Linda Creek at Champion Oaks Drive (City of Roseville, High Water Mark). Creek water inside a house is a flood-policy claim, not a homeowners claim.
233 homes out of the floodplain and a Class 1 rating
After 1995 the Linda Creek project took 233 homes out of the floodplain, and 27 of 44 eligible homeowners elevated their houses. Roseville became the first city in the United States to hold a Class 1 rating in FEMA’s Community Rating System, which lowers flood insurance premiums for property owners (City of Roseville).

Water damage claims in Roseville
Dry Creek and its tributaries run through the city and rise quickly when atmospheric river storms stall over the foothills. On the interior side, losses come from supply line fittings, water heaters, and appliance hoses in homes now twenty to thirty years old.
Our Expertise: We follow water under flooring and into wall assemblies on slab construction, then document the readings so the mitigation scope reaches every wet material rather than the obvious ones.
The Hidden Risk: A carrier may argue that damage in newer housing is a construction defect and therefore excluded. Many policies still cover the resulting damage, and proving that requires evidence gathered before demolition.

Storm and wind damage claims in Roseville
Winter systems and spring thunderstorm activity bring strong straight-line winds, and hail occasionally accompanies them. Concrete tile roofs crack, ridge pieces move, composition shingles lift, and long stretches of fencing come down across newer subdivisions.
The Accurate Advantage: Tile and modern composition roofs hide storm damage well. We get onto the roof, inspect the underlayment where tiles are broken, and document each plane so nothing is dismissed from the ground.
Wind and Rain Impact: A compromised roof lets water into the sheathing during the next storm cycle. Recording the storm date and the damage progression keeps the interior repairs inside the covered loss.
Fire damage claims in Roseville
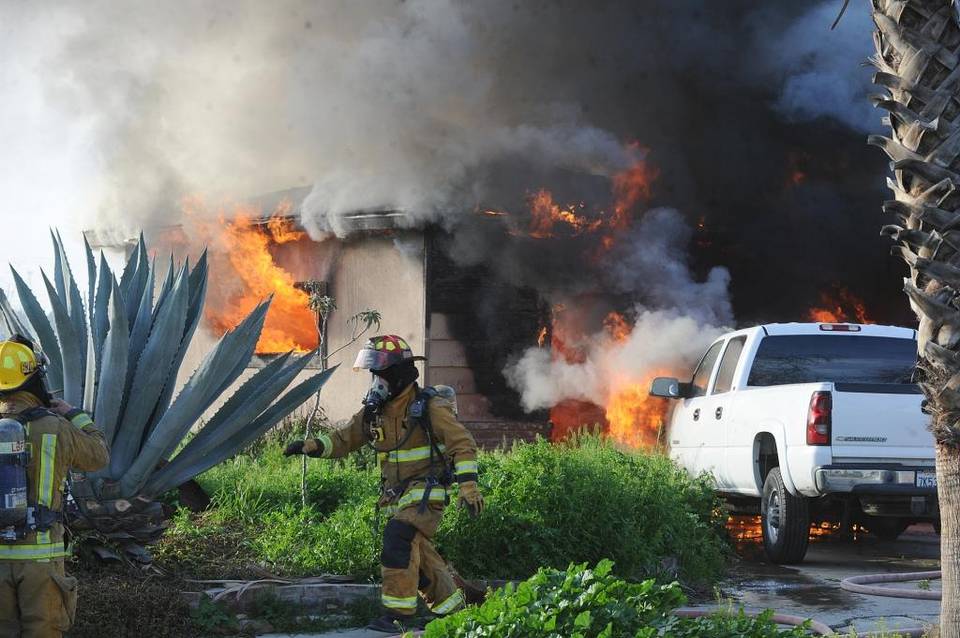
In closely spaced subdivisions a fire can involve neighboring structures rapidly, and open floor plans with shared attic volume carry smoke through an entire house even when flames are confined to one room.
What We Do: We inventory contents in detail, work with specialists to assess heat damage to trusses, wiring, and HVAC systems, and make sure additional living expense benefits are claimed while you are out of the home.
Code Compliance: Rebuilding must meet the current California Building Standards Code and City of Roseville permit requirements, and upgrade obligations appear even on relatively new homes. Ordinance or Law coverage exists to absorb that cost.
Wildfire and smoke damage claims in Roseville
Placer County rises from the valley floor into the Sierra foothills, and the grass and oak woodland east of the city carries fire readily once summer sets in. Smoke from foothill and Sierra fires drifts over Roseville and lingers under valley inversion conditions.
Smoke and Ash Are Real Damage: Homes here run air conditioning for months, pulling ash into filters, ductwork, and insulation. Documented contamination is a covered property loss, not a housekeeping issue.
Foothill Interface Exposure: Along the eastern edge of the city, radiant heat from a fast grass fire damages vinyl fencing, irrigation, siding, and window seals well ahead of any flame contact.
Reasons Roseville owners choose Accurate Claims Consulting
- Local Cost Insight: We estimate with current Placer County construction pricing rather than the dated regional averages carriers rely on.
- Expert Negotiation: We identify where a scope was trimmed and rebuild it line by line with supporting documentation.
- Contingency-Based Service: Your inspection and policy review are free, and we collect a fee only from money we recover.
- Full Claim Management: We prepare the Proof of Loss, handle supplements, and keep the carrier to the schedule the policy requires.
Three steps for a Roseville claim
- Inspect and document. We get onto tile and composition roofs, follow water under slab flooring and into walls, and record ash in filters and ductwork.
- Estimate and file. We build the estimate with Placer County construction pricing and City of Roseville permit requirements, then file it with the supporting evidence.
- Negotiate and settle. We negotiate line by line until the carrier pays what the policy owes. We only get paid when your insurance company pays the claim.
In California, public adjusters are licensed by the California Department of Insurance; its consumer services help policyholders with claim disputes. The National Association of Public Insurance Adjusters (NAPIA) is an industry resource on the profession.
Roseville claims we handle
Select the claim that matches your Roseville loss to see how we document it and which records to keep.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
Other Northern California cities
Beyond Roseville, our Northern California work includes Sacramento, Redding, Oakland, San Francisco, San Jose and Vallejo. Every city is listed on the Northern California page.
Roseville claim questions
Roseville has a Class 1 flood rating. Do I still need flood insurance?
The rating lowers what Roseville owners pay for flood insurance; it does not make a homeowners policy cover floods. Water from Dry Creek or any other creek still needs a separate flood policy.
Does my Roseville policy cover creek flooding?
No. Rising water from Dry Creek or any other channel is excluded from standard homeowners coverage and requires a separate flood policy. Storm damage to the roof and interior plumbing failures are different perils and are ordinarily covered.
Is hail damage to my roof covered?
Hail is a covered peril in many homeowners policies. The dispute is usually whether the marks are hail or ordinary weathering, which is settled with a proper roof inspection and storm-date records rather than opinion.
How is a public adjuster paid?
On contingency. The inspection and policy review are free, and our fee is a percentage of what we recover, set out in writing before you sign anything.
Talk to a Roseville public adjuster
Get the claim settlement you deserve. Cracked tile after a wind event, a supply line failure on a slab, or ash through the HVAC system after a foothill fire all warrant an independent look at your policy first.
Call us today or send the form for a free, no-obligation claim inspection anywhere in Roseville. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.