Public adjuster in Concord, CA for denied or underpaid claims
Accurate Claims Consulting are licensed public adjusters working for Contra Costa County property owners. When a carrier sends its own adjuster, that person values the loss for the insurance company; we do the same work on your side of the file. Our fee comes out of the settlement, so we only get paid when your insurance company pays the claim.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › Concord
Concord homes and businesses we help
Concord is a postwar suburb that filled in quickly, so a large share of the city is single-story tract housing from the 1950s and 1960s with original slabs, aging roofs, and electrical panels that predate every modern appliance in the kitchen. Neighborhoods on the eastern side climb toward open hills below Mount Diablo.
- Owners of 1950s and 1960s single-story tract homes with original slabs, aging roofs and older electrical panels
- Homeowners in the eastern neighborhoods that climb toward the grass and brush below Mount Diablo
- Landlords and business owners with damaged rental or commercial property in Concord
New claim, slow claim, low offer or denial letter: a Concord file can come to us at any of those stages.
Client feedback and settlements


He is very knowledgeable.
Sonia Rivera, Google review
- Slab leak, San Diego, CA (February 2021). A slab leak caused water and foundation damage, and the insurer denied the claim as a long-term leak. We reopened the claim and secured a $247,000 settlement for the homeowners. San Diego slab leak case
- Electrical fire, Los Angeles, CA (October 2021). The insurance company tried to deny the claim, calling the fire arson. We submitted evidence that the fire was accidental and secured a $250,000 settlement. Los Angeles electrical fire case
Our adjusters worked for major insurance companies like Farmers, State Farm and Allstate before they began representing Concord policyholders. See the project gallery and our Google and Yelp reviews.
Concord risk profile
Concord has its own hazard plan, its own fault and its own flood insurance rating. Each one shapes how a claim here should be documented.
A city hazard plan approved by FEMA in 2023
The City of Concord adopted its updated Local Hazard Mitigation Plan on March 28, 2023, and FEMA gave final approval on April 18, 2023; the plan is valid for five years (City of Concord LHMP).
The Concord fault and the 1955 earthquake
The Concord fault runs about 12 miles from Mount Diablo to the Carquinez Strait. Its largest recorded event was a magnitude 5.4 earthquake on October 24, 1955, and a May 2015 swarm under the city produced more than twenty quakes, the largest a 3.6 (UC Berkeley Seismological Laboratory). Cracked drywall after a quake needs earthquake cover; a pipe it breaks may not.
Concord flood insurance discount: 15% as of June 2024
Concord holds a Community Rating System rating of 7 as of June 2024, which gives Concord policyholders a 15% discount on flood insurance premiums (City of Concord flood zone information). Flood water is excluded from a standard homeowners policy, so we check for a separate flood policy before a creek-side claim is filed.

Water damage claims in Concord
Winter storms drop heavy rain onto hard inland soil, and runoff heads for the creek channels that thread through the city. Inside homes, decades-old supply lines, slab leaks, and failed water heaters are all common sources of water damage across central Contra Costa.
Our Expertise: Slab construction hides water beneath flooring and inside base plates. We use moisture mapping and thermal imaging to establish where the damage really stops rather than accepting an estimate drawn at the doorway.
The Hidden Risk: A pinhole leak that ran for weeks gives a carrier grounds to call the damage gradual. Documentation of the failure itself, and of the moisture pattern, is what keeps the claim alive.

Storm and wind damage claims in Concord
Diablo winds arrive dry and strong in autumn, and winter fronts bring gusts with rain behind them. Both events lift roofing, flatten long fence runs, damage patio covers, and drop limbs from the mature trees planted throughout the older subdivisions.
The Accurate Advantage: We check the full roof plane, fasteners, and edge details rather than the single damaged area, since wind that displaced one section has almost certainly loosened others.
Wind and Rain Impact: Once roofing is compromised, the following storm carries water to the sheathing and the ceiling below. Tying that damage to the original wind event keeps it in one covered claim.
Fire damage claims in Concord
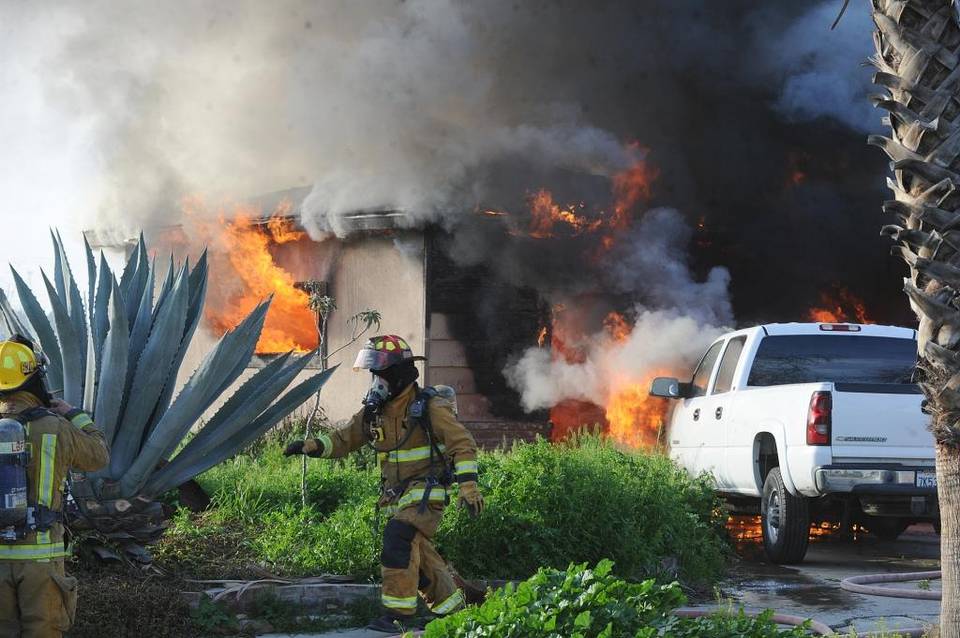
Fires in older Concord housing often start with electrical systems or in garages, and single-story homes with continuous attic space let smoke and heat travel across the entire structure quickly.
What We Do: We prepare a detailed contents inventory, bring in specialists to identify heat-compromised framing and wiring, and document the smoke damage that reaches rooms the fire never entered.
Code Compliance: Repairs must meet the current California Building Standards Code and City of Concord permitting, and on a home built sixty years ago that can require substantial upgrades. Ordinance or Law coverage is the provision that pays for them.
Wildfire and smoke damage claims in Concord
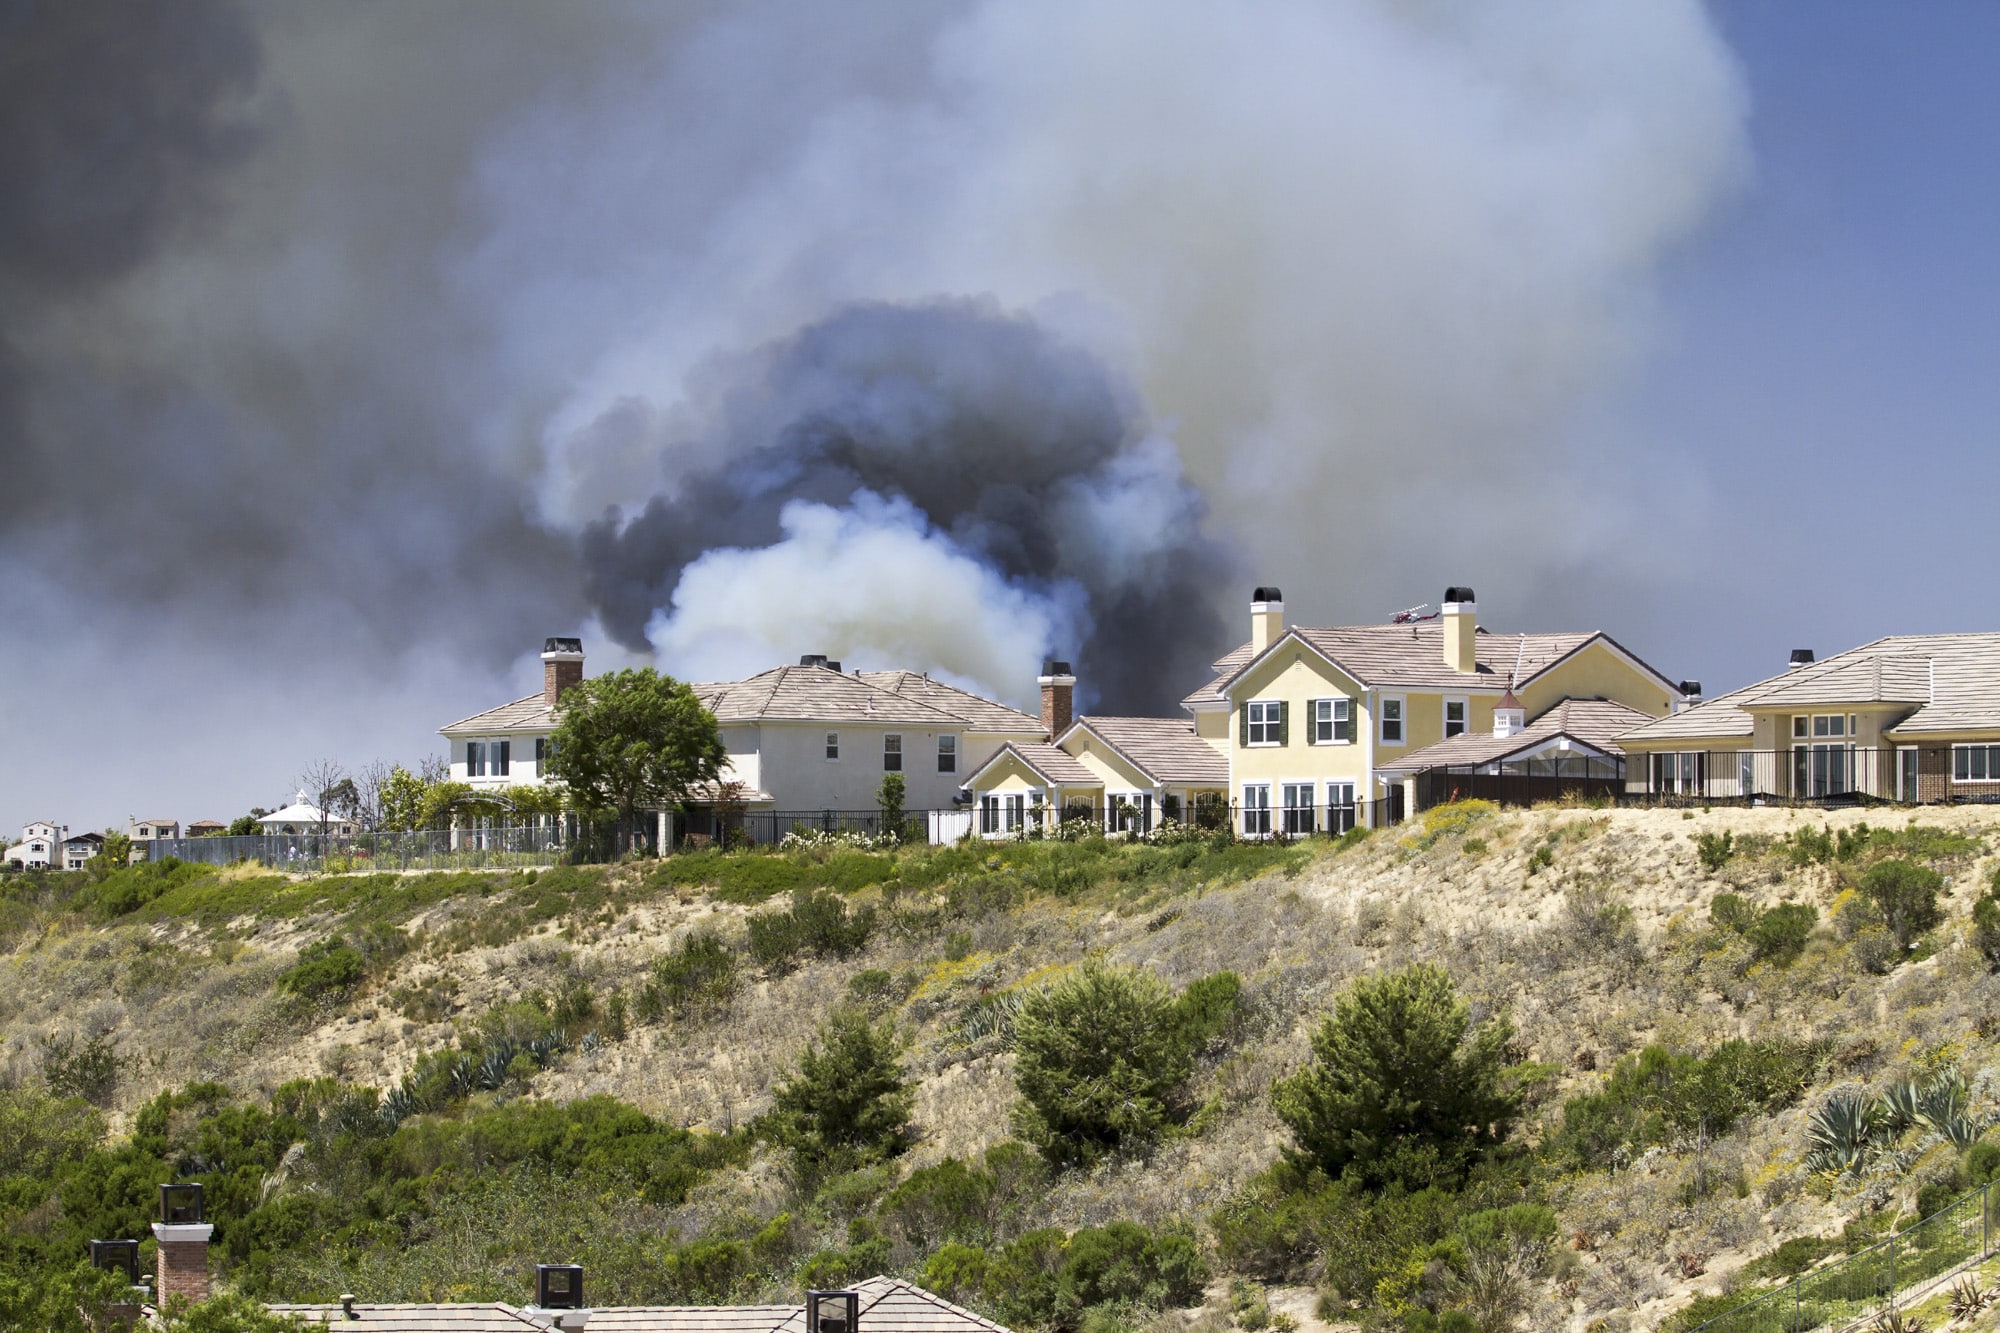
The open grass and brush on the slopes below Mount Diablo cure early and burn fast, and the neighborhoods along that edge sit in a genuine wildland urban interface. Regional smoke from fires elsewhere in Northern California settles over the whole Diablo Valley.
Smoke and Ash Are Real Damage: Ash enters attics, ducts, and insulation and settles into fabrics. When it is documented it is a covered loss, and when it is not it becomes a cleaning credit that does not cover remediation.
Interface Exposure: Radiant heat from a grass fire damages fencing, siding, window seals, and rooflines without ever igniting a home, and that damage is regularly omitted from the first carrier estimate.
Why Concord owners choose Accurate Claims Consulting
- Local Cost Insight: Contra Costa County labor rates and material pricing exceed the regional averages loaded into carrier estimating software.
- Expert Negotiation: We know which line items get cut first and how to put them back with evidence.
- Contingency-Based Service: The inspection and policy review are free, and we are paid only from a recovery.
- Full Claim Management: Proof of Loss, supplements, and correspondence with the carrier all move to us.
Three steps from loss to settlement in Concord
- Inspect and document. We map moisture under slab flooring, check the full roof plane and record every room smoke reached.
- Estimate and file. We build the repair estimate at Concord and Contra Costa County costs, code upgrades included, and file it with the evidence.
- Negotiate and settle. We handle the insurer until the claim is settled. We only get paid when your insurance company pays the claim.
Licensing for California public adjusters comes from the California Department of Insurance, which is also where policyholders take claim questions and complaints. The National Association of Public Insurance Adjusters (NAPIA) is an industry resource on the work public adjusters do.
Concord claims we handle
Every claim below is handled by the same team that works your Concord file, from the first inspection to the final settlement figure.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
More cities in our Northern California area
Beyond Concord, policyholders in Vallejo, Sacramento, Roseville, Redding, San Francisco and San Jose work with us too. Browse the Northern California service area.
Concord claim questions
Does my policy cover the fence and the landscaping?
Fences, sheds, and other detached structures usually fall under a separate limit within the policy, and trees and shrubs are covered for specific perils only. Those limits are easy to overlook, so they are worth checking on every storm claim.
Is roof damage from a Diablo wind event one claim or several?
Usually one. When dry autumn gusts lift roofing and the next rain soaks the sheathing and ceiling, we tie the interior damage to the original wind event so it stays in a single covered claim.
Is smoke from a grass fire below Mount Diablo a covered loss?
Smoke and ash that reach attics, ducts and insulation are physical damage when they are documented. Radiant heat damage to fencing, siding and window seals belongs in the same claim even if the house never caught fire.
Can I still hire you if the insurer already denied my claim?
Yes. A denial is the insurer’s position, not the last word. We test the stated reason against the policy wording and the evidence, and a properly documented file can turn a denial around.
Talk to a Concord public adjuster
Get the claim settlement you deserve. A slab leak in a Clayton Valley ranch home, wind damage after a Diablo event, or smoke through the attic after a hill fire all deserve a proper independent evaluation.
Call us today or complete the form to schedule your free, no-obligation Concord claim inspection. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.