Public adjuster in Santa Rosa, CA for denied or underpaid claims
Accurate Claims Consulting works throughout Santa Rosa and Sonoma County as licensed public adjusters. We are hired by the property owner, and our job is to establish what was lost, what the policy promises, and what it will take to get the carrier to that number. Our fee is contingent: we only get paid when your insurance company pays the claim.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › Santa Rosa
Who we help in Santa Rosa
Santa Rosa is a city that has already lived through catastrophic wildfire, and that experience shapes how property owners here think about insurance. Between the Victorians of the West End, hillside homes above Fountaingrove, and neighborhoods rebuilt within the last decade, the range of construction in this city is unusually wide.
- Owners of Victorian and older homes in the West End
- Hillside homeowners in Fountaingrove
- Owners of Santa Rosa homes rebuilt after the 2017 fires
Whether your Santa Rosa claim is new, stalled, underpaid or already denied, we can step in.
What clients say, and what we recovered


Thankful is an understatement. I can’t express the gratitude I have for this company and what they stand for.
Vanessa Mitchell, Google review
- Slab leak, San Diego, CA (February 2021). The leak caused water and foundation damage, and the insurer initially denied the claim as a long-term leak. Accurate reopened the claim and secured a $247,000 settlement. San Diego slab leak case
- House fire, Laguna Beach, Orange County, CA (October 2020). A fire that started in the attic caused structural and roof damage. The insurer offered the homeowners $46,583 and we secured a $351,216 settlement. Laguna Beach house fire case
Every adjuster on a Santa Rosa file evaluated losses for Farmers, State Farm and Allstate before switching sides to represent policyholders. Our recent projects and reviews pages have more.
Santa Rosa after 2017: the numbers
Santa Rosa has its own fire and rainfall record, and three figures from it shape how we approach a claim here.
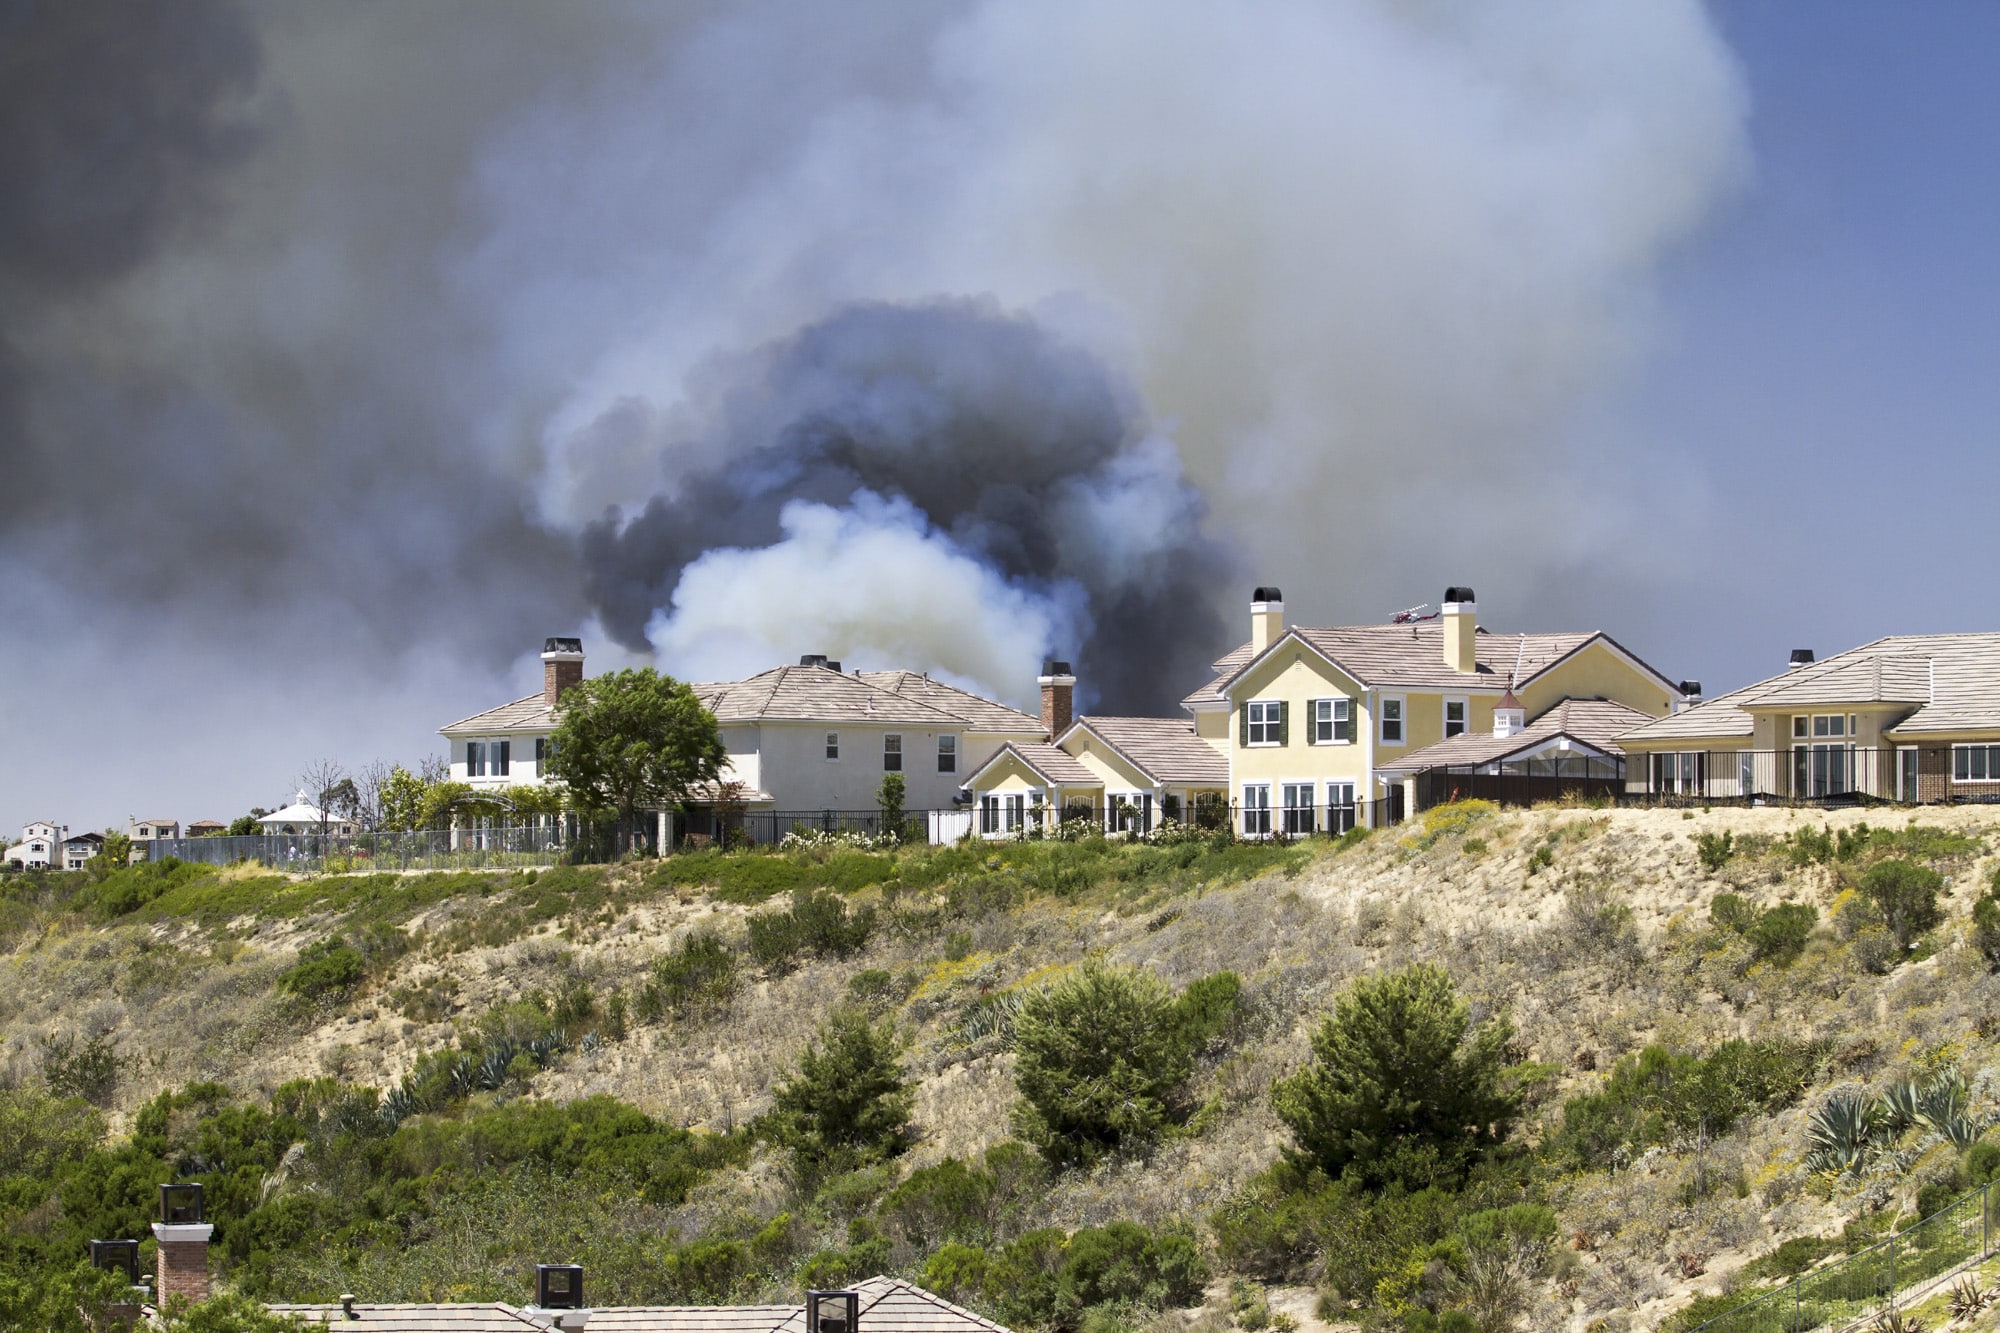
3,043 Santa Rosa homes lost in October 2017
The October 2017 wildfires destroyed more than 5,300 homes, including 3,043 within the City of Santa Rosa, approximately 5 percent of the city housing stock. They took 24 lives and caused an estimated 100,000 people to evacuate countywide (City of Santa Rosa, October 2017 Wildfires).
Hazard plan adopted December 7, 2021
Santa Rosa adopted the Sonoma County Multijurisdictional Hazard Mitigation Plan, which carries a City of Santa Rosa annex in Volume 2, on December 7, 2021 (City of Santa Rosa, Local Hazard Mitigation Plan). The plan runs on a five-year cycle.
2.23 inches in one day, January 2023
On January 9, 2023 the Santa Rosa station recorded 2.23 inches of rain, above the previous record of 2.13 inches from 1995 over a 120-year period of record (NOAA California Nevada River Forecast Center). Rain on that scale finds weak roofs and windows quickly.

Water damage claims in Santa Rosa
Atmospheric river storms move up the Russian River watershed and dump rain over saturated ground, and Santa Rosa Creek and Mark West Creek both respond quickly. Roof and window leaks follow, while inside the home older supply plumbing and failed water heaters cause interior losses.
Our Expertise: We trace water into subfloors, wall cavities, and crawl spaces, then document the readings so a drying scope covers the whole affected assembly instead of the visible room.
The Hidden Risk: In a wet North Bay winter, materials do not dry on their own. An underscoped mitigation turns into microbial growth, and by then the carrier is arguing about causation rather than paying for repairs.

Storm and wind damage claims in Santa Rosa
North Bay winter systems bring rain and wind together, and dry offshore winds arrive in autumn under very different conditions. Both drop oaks and pines onto roofs, tear off ridge caps and flashing, and take out fencing and outbuildings.
The Accurate Advantage: We evaluate the entire roof system and the surrounding structures, since detached garages, sheds, fences, and landscaping have coverage under many policies and can be left out of a first estimate.
Wind and Rain Impact: Displaced roofing lets the following storm into the attic. We document that progression so the interior damage is not reclassified as a maintenance issue.
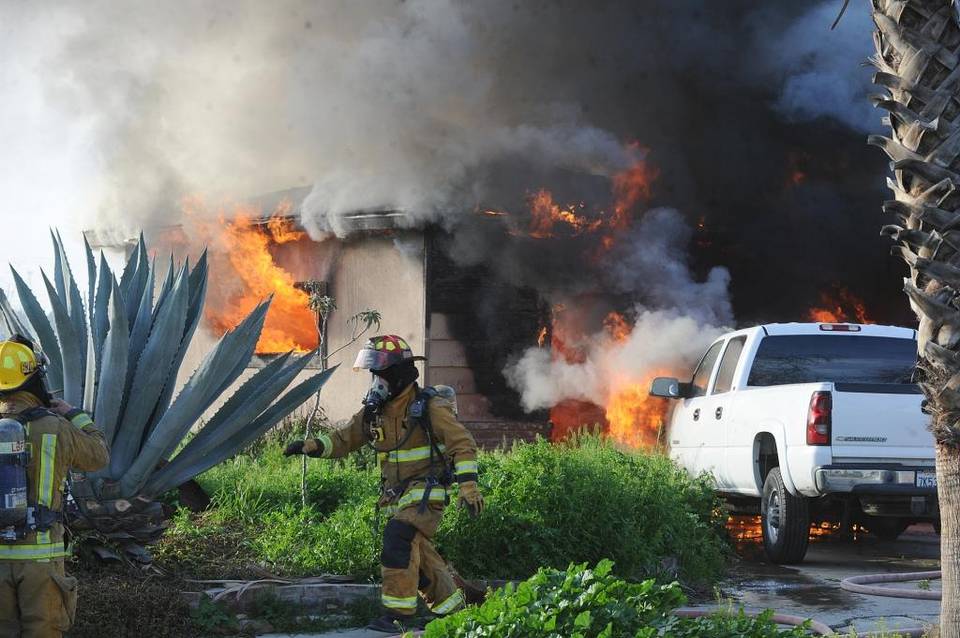
Fire damage claims in Santa Rosa
Structure fires here range from kitchen and electrical fires in older housing to total losses. Where a home is destroyed, the claim becomes a lengthy process involving contents valuation, additional living expenses, and a rebuild estimate that must reflect real local construction costs.
What We Do: We prepare a detailed contents inventory, coordinate with construction professionals on the rebuild scope, and track additional living expense benefits so they are not quietly exhausted before the home is finished.
Code Compliance: Reconstruction must meet the current California Building Standards Code plus local requirements, and rebuilding to today’s standards can cost substantially more than the original structure. Ordinance or Law coverage exists to bridge that gap when it is properly claimed.
Wildfire and smoke damage claims in Santa Rosa
Wildfire is not a hypothetical risk in Sonoma County. The hills east of the city sit in a wildland urban interface, and smoke from North Bay fires can settle over the valley for days at a time.
Smoke and Ash Are Real Damage: A house that survives a fire can still be uninhabitable. Ash and soot penetrate insulation, ducts, cabinetry, and clothing, and that contamination is a covered loss when it is documented rather than assumed.
Policy Limits Deserve Attention: Some owners only discover their dwelling limit is short of true rebuild cost after a total loss. We read those limits, extended replacement cost provisions, and endorsements carefully before advising anyone on strategy.
Why Santa Rosa owners hire Accurate Claims Consulting
- Local Cost Insight: Sonoma County rebuild pricing, trade availability, and permit timelines differ sharply from the statewide figures a carrier estimate assumes.
- Expert Negotiation: We know where a scope was thinned and how to document the difference item by item.
- Contingency-Based Service: The initial inspection and policy review are free, and we are paid only from a recovery.
- Full Claim Management: Proof of Loss, contents schedules, supplements, and deadlines all become our responsibility.
How we work a Santa Rosa claim
- Inspect and document. We go through crawl spaces, subfloors and attics, photograph roof systems and outbuildings, and test for smoke and ash before anything is cleaned.
- Estimate and file. We price the work at Sonoma County rebuild costs and City of Santa Rosa permit requirements, then file it with the supporting evidence.
- Negotiate and settle. We work through each line with the carrier until the policy is paid as written. We only get paid when your insurance company pays the claim.
California public adjusters are licensed by the California Department of Insurance; its consumer pages explain how to raise a claim complaint. Background on the profession is available from the National Association of Public Insurance Adjusters (NAPIA), an industry resource.
Santa Rosa claims we take on
These are the claim types our public adjusters take on for Santa Rosa residents and business owners.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
Other cities near Santa Rosa
Outside Santa Rosa we also represent owners in Concord, Sunnyvale, Roseville, Elk Grove, Hayward and Redding, and the Northern California page lists every city we cover.
Santa Rosa claim questions
What if my dwelling limit is not enough to rebuild?
Check for extended or guaranteed replacement cost provisions, building code upgrade coverage, and any inflation endorsement, because those can add meaningful amounts above the stated limit. We review the full declarations page and all endorsements before anyone concludes the limit is final.
How are additional living expenses handled during a long rebuild?
Most policies pay reasonable additional costs of living elsewhere for a defined period or limit. Those benefits are easy to leave unused when receipts are not tracked and submitted, and we make sure they are claimed.
My Santa Rosa home was rebuilt after 2017. Should my coverage change?
Check it. A rebuilt house can cost more to replace than the one it replaced, so the dwelling limit, any extended replacement cost provision and building code upgrade coverage should match the new structure.
The insurer assigned an adjuster. Why hire my own?
The adjuster the insurer sends is accountable to the insurer. A public adjuster answers to you, builds an independent estimate of the loss and negotiates the difference.
Talk to a Santa Rosa public adjuster
Get the claim settlement you deserve. Whether you are facing a water loss in an older West End home, storm damage to an outbuilding, or a fire claim that is not moving, an independent review of your coverage costs nothing.
Call us today or send the form to schedule your free, no-obligation Santa Rosa claim inspection. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.