Public adjuster in Redding, CA for denied or underpaid claims
Accurate Claims Consulting serves Redding and Shasta County property owners as licensed public adjusters. Our clients are property owners, never insurers, and our work is to prove the loss and hold the carrier to the policy it sold. Our fee is contingent: we only get paid when your insurance company pays the claim.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › Redding
Who we help in Redding
Redding sits at the north end of the Sacramento Valley where the terrain closes in and the wildland begins almost immediately outside the city limits. Property here ranges from established neighborhoods and downtown commercial buildings to rural parcels, outbuildings, and manufactured homes on acreage, and each carries its own coverage complications.
- Homeowners in Redding neighborhoods on both sides of the Sacramento River
- Owners and tenants of downtown Redding commercial buildings
- Owners of larger parcels inside the city with detached shops, outbuildings or manufactured homes
We take Redding claims at any stage: freshly filed, waiting on the carrier, underpaid or denied.
Client reviews and recent settlements


Thank goodness the repairs to my water-damaged condo have been completed. I had never had a claim against my insurance before.
rock roades, Google review
- Toilet overflow, Culver City, CA (July 2022). Mercury Insurance intended to deny this water damage claim when the homeowner hired us. We secured a $136,841 settlement. Culver City toilet overflow case
- Electrical fire, Los Angeles, CA (October 2021). The insurance company tried to deny the claim, calling the fire arson. We submitted evidence that the fire was accidental and secured a $250,000 settlement. Los Angeles electrical fire case
The adjusters on a Redding claim learned how carriers evaluate losses while working at Farmers, State Farm and Allstate. More results are on our recent projects page, and every client review is on our reviews page.
Redding fire risk on the record
Three published figures explain why fire documentation carries so much weight on a Redding claim.
270 Redding homes lost in the Carr Fire
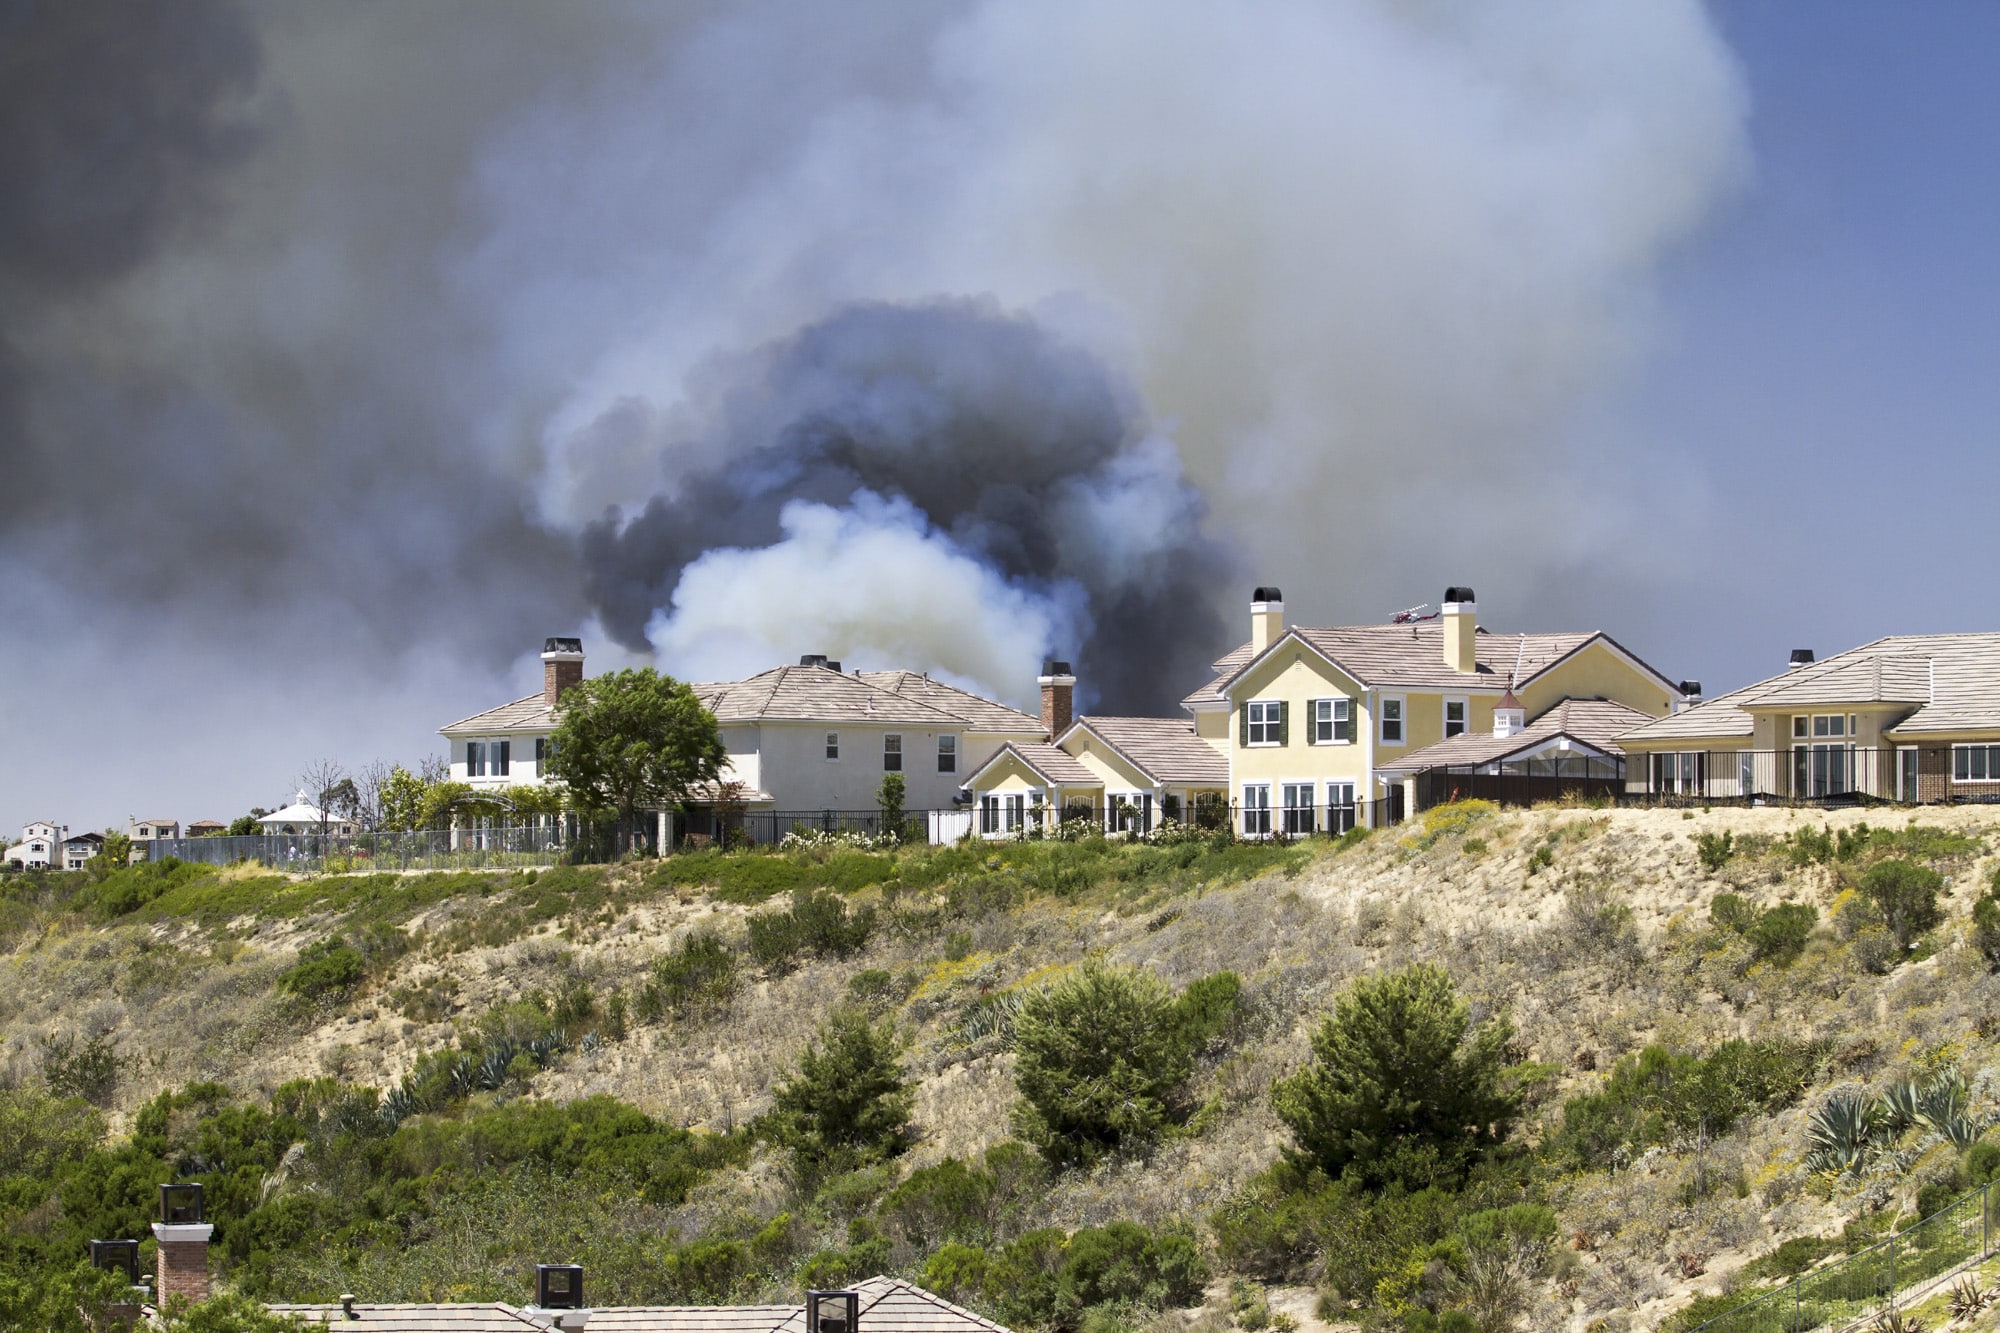
In July 2018 the Carr Fire moved into Redding city limits. It killed eight people and destroyed over 2,000 structures in Shasta County, including 270 homes within Redding (Redding Electric Utility Wildfire Mitigation Plan, revised May 1, 2023).
Close to half of the utility territory is high fire threat
Redding Electric Utility serves 61 square miles. The same plan places 33.5% of that area in CPUC High Fire Threat District Tier 2 and another 12.5% in Tier 3. Owners there should keep photos and receipts for roofing, vents and defensible-space work, because those records answer the first questions an insurer asks after a fire.
A fire vortex with EF-3 strength winds
On 26 July 2018, after the Carr Fire jumped the Sacramento River toward western Redding, a fire-generated vortex formed with surface winds estimated above 64 m/s (about 143 mph), equivalent to an EF-3 tornado (Lareau et al., The Carr Fire Vortex, NOAA Institutional Repository). Wind damage caused during a fire is part of the same loss and should be documented with it.

Water damage claims in Redding
Winter storms come off the Trinity and southern Cascade ranges and drop rain fast on ground that sheds it quickly, and roof and window intrusion follows. Inside, supply lines, water heaters and pipes that freeze during the cold snaps at this end of the valley cause the interior losses.
Our Expertise: We map moisture into framing, insulation, and subfloor, and on larger parcels we include outbuildings, wells, and pump houses that a carrier estimate can leave out.
The Hidden Risk: A freeze failure raises questions about whether the property was heated or maintained. Those defenses are answerable, but only with facts documented at the outset.

Storm and wind damage claims in Redding
Wind funneled by the terrain around the north valley lifts roofing, brings pines and oaks down onto structures, damages carports and outbuildings, and strips metal roofing.
The Accurate Advantage: We document the entire property, not just the house. Detached garages, shops, barns, fencing and equipment sheds carry their own coverage under many policies and belong in the estimate.
Wind and Rain Impact: Displaced roofing lets the next storm reach the attic and ceilings. Recording the causal sequence keeps that interior damage tied to the covered wind event.
Fire damage claims in Redding
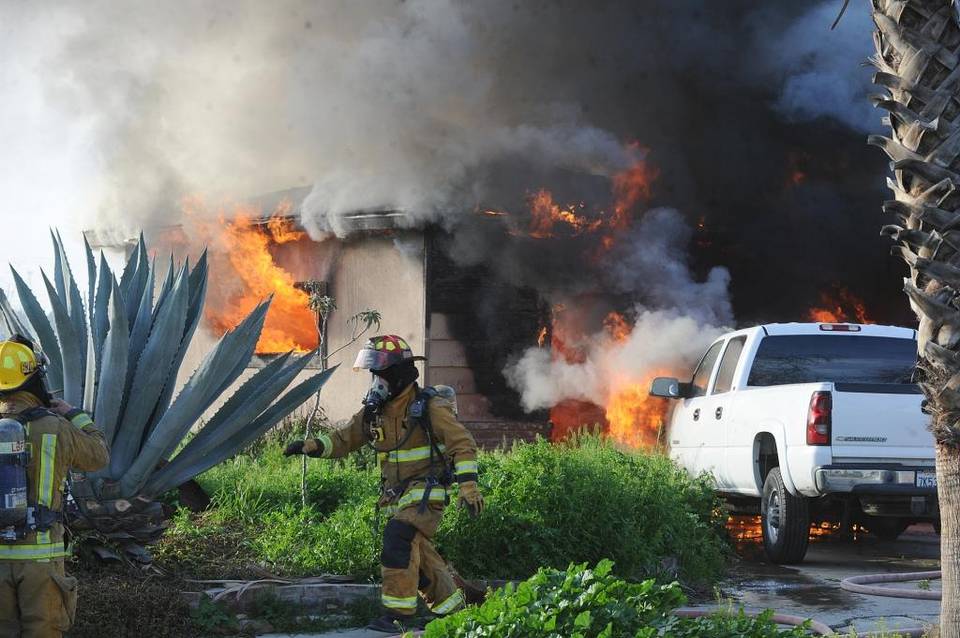
Shasta County knows fire. Beyond wildland events, structure fires here start with extreme summer heat, older electrical systems, and heating equipment worked hard through the winter, and the resulting claims are rarely simple.
What We Do: We prepare a full contents inventory, retain specialists to evaluate heat damage to structure and systems, and pursue additional living expenses while the property is uninhabitable, including for households with limited nearby housing.
Code Compliance: Rebuilding must meet the current California Building Standards Code, which in this region includes wildland urban interface construction requirements for materials such as roofing, vents, and exterior finishes. Ordinance or Law coverage is what pays for those mandated upgrades.
Wildfire and smoke damage claims in Redding
Wildland starts at the edge of Redding. Fire season brings ember exposure, radiant heat, and smoke that can settle into the valley for weeks, and residents saw in 2018 how quickly a fire can move under extreme conditions.
Smoke and Ash Are Real Damage: A structure left standing can still be heavily contaminated. Ash in insulation, ducts, and contents is covered physical damage, and establishing its extent takes testing rather than a walkthrough.
Total Loss Claims: Where a home is destroyed, the fight moves to policy limits, rebuild cost, contents valuation, and debris removal. We handle each of those as its own documented component instead of accepting a single lump figure.
Why Redding owners choose Accurate Claims Consulting
- Local Cost Insight: Contractor availability in the north state tightens sharply after a major fire, and rebuild pricing reflects that. Carrier software rarely does.
- Expert Negotiation: We know how a scope gets reduced and how to restore it with photographs, measurements, and documented pricing.
- Contingency-Based Service: The inspection and policy review cost nothing, and our fee comes only out of a recovery.
- Full Claim Management: Proof of Loss, contents schedules, supplements, and deadlines are ours to manage.
How a Redding claim moves forward
- Inspect and document. We walk the house and every outbuilding, photograph roof and siding, and record smoke and ash in ducts and insulation before cleanup starts.
- Estimate and file. We price the repair with current north-state contractor rates and City of Redding permit requirements, then file it with the evidence.
- Negotiate and settle. We take the carrier through the estimate line by line until the policy is paid in full. We only get paid when your insurance company pays the claim.
Public adjusters in California hold a license from the California Department of Insurance, which also helps consumers with claim complaints. For background on the profession, the National Association of Public Insurance Adjusters (NAPIA) is an industry resource.
Claims we handle in Redding
These are the claim types our public adjusters take on for Redding residents and business owners.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
Areas we serve near Redding
From Redding, our Northern California coverage reaches Sacramento, Stockton, Vallejo, Oakland, San Francisco and San Jose; the full list is on the Northern California service area page.
Redding claim questions
Are my barn, shop, and fencing covered under my homeowners policy?
Detached structures usually fall under a separate limit, often a percentage of the dwelling limit, and that amount can be far short of replacing a large shop or long stretches of fence. Reviewing those limits matters most before a loss, but they still have to be claimed in full afterward.
My home survived the fire but everything smells of smoke. Now what?
Document it before you clean. Smoke and ash contamination is covered physical damage under most policies, and the scope of remediation is established through testing and detailed inspection, not by how a room looks.
Is debris removal part of my fire claim?
Most policies include debris removal coverage, often subject to a limit or a percentage of the loss. On a total loss it is a significant number, and it should be documented separately rather than folded into a lump sum offer.
The insurer assigned an adjuster. Why hire my own?
The company adjuster writes the estimate the insurer pays from. A public adjuster works only for you, documents every building on the parcel, and argues the claim against that estimate.
Talk to a Redding public adjuster
Get the claim settlement you deserve. Whether you are dealing with a burst pipe after a freeze, wind damage to a shop building, or a wildfire claim that has stalled, an independent review of your policy costs you nothing.
Call us today or complete the form to arrange a free, no-obligation inspection of your Redding property. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.