Public adjuster in Santa Clara, CA for home, rental and commercial claims
Accurate Claims Consulting represents Santa Clara homeowners, landlords and business owners as licensed public adjusters. We work for the policyholder, not the insurer: we document the loss, read the policy and press the carrier for what the coverage actually owes. Our fee is contingent, so we are paid only when your insurance company pays the claim.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › Santa Clara
Who we help in Santa Clara
Santa Clara puts mid-century houses, newer condominiums and a large stretch of office and light industrial space inside one city boundary. A single winter storm can mean a modest roof claim on one street and a business interruption claim a few blocks away, and carriers treat those two files very differently.
- Owners of mid-century homes around the Old Quad
- Condo and townhome owners in Rivermark
- Landlords and business owners with commercial and light industrial buildings north of US-101
New claim, stalled claim, low offer or outright denial: we can take a Santa Clara file at any stage.
Client words and recent results


He went over all our options and walked us through all the necessary steps to take. He was always quick to respond to any questions we had.
Diane Klein, Google review
- Burst toilet supply line, Los Angeles, CA (July 2021). The insurer tried to deny this vacation-home claim as a long-term leak. We got the claim covered and secured a $537,000 settlement. Los Angeles supply line case
- Attic fire, San Diego, CA (March 2022). A fire that started in the attic did heavy damage to the home. The insurer offered $92,000 and we secured a $311,000 settlement. San Diego attic fire case
Before representing Santa Clara policyholders, our adjusters handled claims for Farmers, State Farm and Allstate. More outcomes are on our recent projects page, and every client review is on our reviews page.
Santa Clara flood risk in three numbers
Creeks cross the city and levees line several of them. The city flood and hazard documents explain why a water claim here needs careful documentation, even well away from a creek.
About 35% of the city sits behind levees
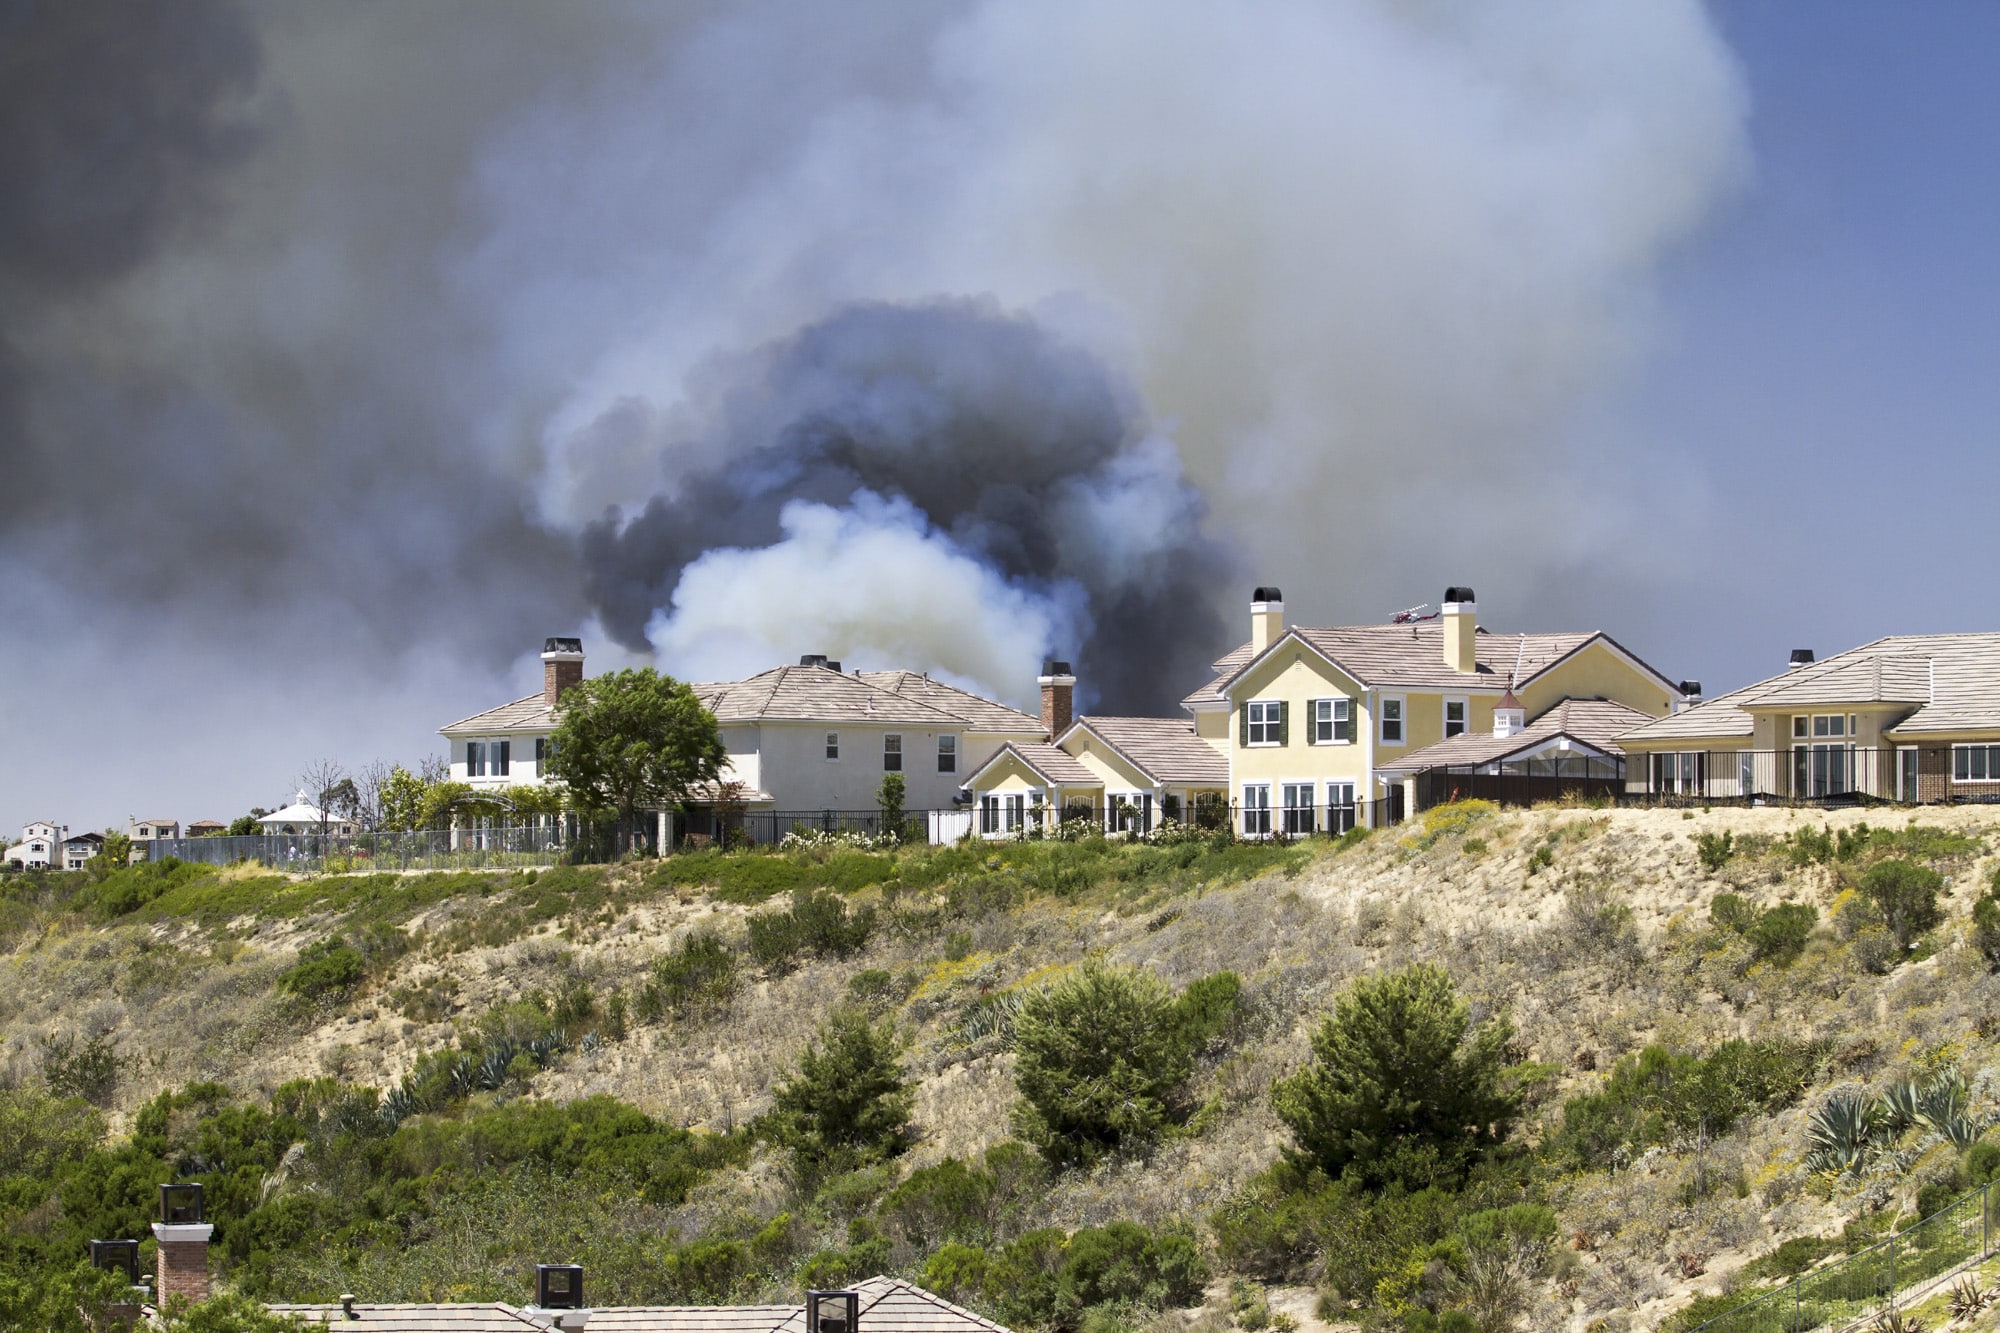
Less than 10% of Santa Clara is inside the FEMA Special Flood Hazard Area, but about 35% of the city is protected by levees, and the city says properties both in and out of the mapped zone face riverine and storm water flooding. Since 1980, over 40% of National Flood Insurance Program payments in the city went to losses outside the Special Flood Hazard Area (City of Santa Clara, Flood Insurance).
Community Rating System class 7, as of July 2025
Santa Clara holds a class 7 rating in the FEMA Community Rating System. That gives a 15% flood insurance premium discount for properties inside the Special Flood Hazard Area and 5% for properties outside it, according to the city flood insurance page last updated July 11, 2025. Ask your agent to confirm the discount appears on your premium.
Hazard plan adopted August 27, 2024
On August 27, 2024 the City Council adopted the Santa Clara County Multi-Jurisdictional Hazard Mitigation Plan together with its City of Santa Clara annex. It covers nine hazards, from earthquake, flood and dam and levee failure to severe weather and wildfire smoke (City of Santa Clara, Council file 24-1433).

Water damage claims in Santa Clara
The city sits on flat valley floor drained by San Tomas Aquino and Saratoga creeks, and heavy winter rain overwhelms storm systems faster than most people expect. Indoors, the usual sources are aging supply lines, water heaters, and irrigation or fire sprinkler failures in commercial buildings.
Our Expertise: Commercial water losses spread laterally through shared floor assemblies and reach tenant improvements, inventory, and equipment. We scope all of it, not just the drywall.
The Hidden Risk: On the residential side, a slow leak behind a wall in a 1950s ranch home is often labelled long-term seepage and denied. Moisture data collected early is the strongest answer to that position.

Storm and wind damage claims in Santa Clara
Winter fronts bring sustained gusts across open, flat terrain with little to break them. Low-slope commercial roofs lose membrane and flashing, residential shingles lift, and rooftop mechanical equipment takes damage that nobody notices until it rains again.
The Accurate Advantage: We include rooftop HVAC units, screens, and penetrations in the inspection, because that equipment is frequently damaged and just as frequently omitted from a carrier estimate.
Wind and Rain Impact: When wind opens the roof, the water that follows becomes part of the same loss. We document the sequence so it is not split into two claims with two deductibles.
Fire damage claims in Santa Clara
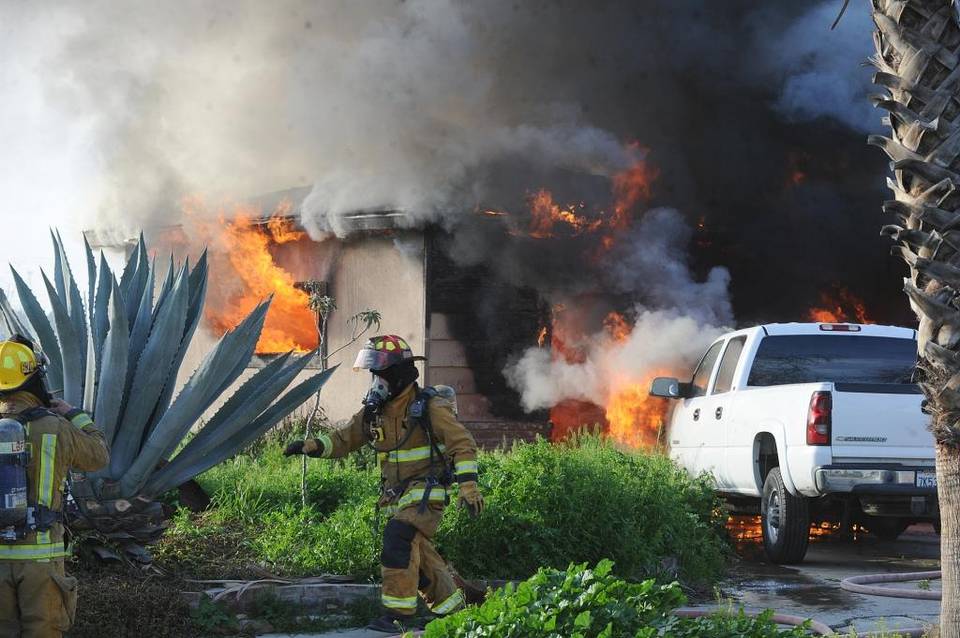
Fire in a residential neighborhood and fire in a commercial or industrial building are entirely different claims. The first turns on contents and living expenses; the second adds equipment, inventory, code compliance, and lost income.
What We Do: We build the contents and equipment inventory, retain specialists to evaluate heat-affected structure and systems, and pursue business interruption coverage where the policy provides it.
Code Compliance: Reconstruction must meet the current California Building Standards Code and City of Santa Clara permitting, which on older buildings can force sprinkler, electrical, or accessibility upgrades. Ordinance or Law coverage is meant to absorb those costs.
Wildfire smoke and ash claims in Santa Clara
Santa Clara has no wildland border, but it sits in a valley that traps smoke drifting in from the Santa Cruz Mountains, the Diablo Range, and fires much farther north. Buildings that run mechanical ventilation continuously pull that particulate straight inside.
Smoke and Ash Are Real Damage: Soot in ductwork, insulation, and stored goods is a physical loss. Documented properly it is payable, and undocumented it becomes a token cleaning allowance.
Commercial Considerations: Sensitive equipment, clean environments, and stored inventory can be affected by ash at levels that look trivial to the eye. Testing establishes what a visual inspection cannot.
Why Santa Clara owners hire Accurate Claims Consulting
- Local Cost Insight: Silicon Valley trade rates, permit timelines, and tenant improvement costs bear little resemblance to the regional averages inside carrier estimating software.
- Expert Negotiation: We identify where a scope was quietly narrowed and press the point with documentation.
- Contingency-Based Service: The first inspection and the policy review cost nothing, and we are paid out of the recovery.
- Full Claim Management: Proof of Loss, supplements, and all carrier correspondence become our job rather than yours.
How we work a Santa Clara claim
- Inspect and document. We check slab floors, wall cavities and low-slope roofs with their rooftop units, and in commercial space we record tenant improvements, equipment and inventory before cleanup starts.
- Estimate and file. We price the repair at Santa Clara County trade rates and City of Santa Clara permit requirements, and add business interruption figures where the policy covers lost income.
- Negotiate and settle. We take the carrier through the estimate line by line until the policy is paid as written. Our fee comes only from what your insurance company pays.
The California Department of Insurance licenses public adjusters in this state, and its consumer help pages set out how to file a complaint about a claim. For general background on public adjusting, the National Association of Public Insurance Adjusters (NAPIA) is a useful industry resource.
Claim types we handle in Santa Clara
Each link below explains how we handle that type of claim for Santa Clara homes, rentals and commercial buildings.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
Nearby cities we also cover
Close to Santa Clara we also work in Sunnyvale, San Jose, Fremont, Hayward and Berkeley. The Northern California page lists every city we cover.
Questions from Santa Clara property owners
My building is behind a levee. Do I still need flood insurance?
The city guidance is yes: properties behind levees and outside the mapped flood zone can still flood, and homeowners and commercial property policies exclude flood. A new flood policy typically has a 30-day waiting period, so it has to be in place before the winter storms arrive.
Does my commercial policy cover lost income after a fire?
Many do, through business interruption and extra expense coverage, but the calculation is detailed and carriers rarely volunteer the full figure. Financial records have to be assembled and presented properly for that part of a claim to be paid.
My tenant improvements were damaged. Who claims them?
It depends on the lease and on both policies. Improvements paid for by a tenant are often insured by the tenant even though they are attached to the landlord building. We review the lease alongside the policies before allocating anything.
Can I hire a public adjuster mid-claim?
Yes. Bringing in your own adjuster after a carrier estimate has already been issued is common, and it is often the point at which the missing scope finally gets documented.
Talk to a Santa Clara public adjuster
Get the claim settlement you deserve. Whether the loss is a flooded tenant suite, wind damage to a low-slope commercial roof, or a leak under a mid-century home near the Old Quad, a review of your policy costs nothing.
Call or use the form to book a free, no-obligation Santa Clara claim inspection. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.