Public adjuster in Oakland, CA for denied or underpaid claims
Accurate Claims Consulting serves Oakland as licensed public adjusters, working only for policyholders. We take over the documentation, the estimating and the negotiating, so the insurer answers to a professional rather than to a homeowner in the middle of a crisis. You pay nothing up front: we only get paid when your insurance company pays the claim.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › Oakland
Who we help in Oakland
Oakland runs from flatland bungalows and Victorians near the estuary up into steep, wooded hills where homes sit at the wildland edge on narrow roads. A city this varied produces very different losses block to block, and a carrier estimate written from a template rarely fits any of them.
- Homeowners in the Oakland hills on steep, wooded lots and in the flatland bungalows and Victorians near the estuary
- Landlords and owners of multi-unit buildings, including converted buildings with several units
- Business owners with a loss to commercial property (see commercial property claims)
We can help whether your claim is new, stalled, underpaid or already denied.
Reviews and recent results


He took care of all the details with the insurance company and really made everything seamless from my end of the claim.
Darlene Clark, Google review (flood in a three-family house)
- Fire, Calexico, CA (March 2022). The insurance company initially denied this fire claim citing a vacancy exclusion. We reversed the denial and secured a $230,000 settlement for the homeowner. Calexico fire case
- Kitchen ice-maker line leak, Los Angeles (August 2022). The insurer was in the process of denying the claim for long-term damage. We secured a $246,021 settlement. Los Angeles kitchen leak case
Our adjusters worked for major insurance companies like Farmers, State Farm and Allstate before they began representing Oakland policyholders. See all recent projects or read all reviews.
Oakland claim profile
The loss behind an Oakland claim depends on where the property sits: hillside homes exposed to fire, older homes in the flats, and buildings on slopes that collect water from uphill. Three local facts shape how we document a claim here.
The city plans for earthquake, flood, landslide and wildfire
The City of Oakland adopted its 2026 to 2031 Local Hazard Mitigation Plan on June 2, 2026. The plan covers dam failure, drought, earthquake, flood, landslide, sea-level rise, severe weather (wind and extreme heat), tsunami and seiche, and wildfire (City of Oakland hazard mitigation plan). For a claim, the cause matters: earth movement is excluded under most homeowners policies, while water entering through a storm-damaged roof or wall is treated differently.
The 1991 Oakland Hills fire
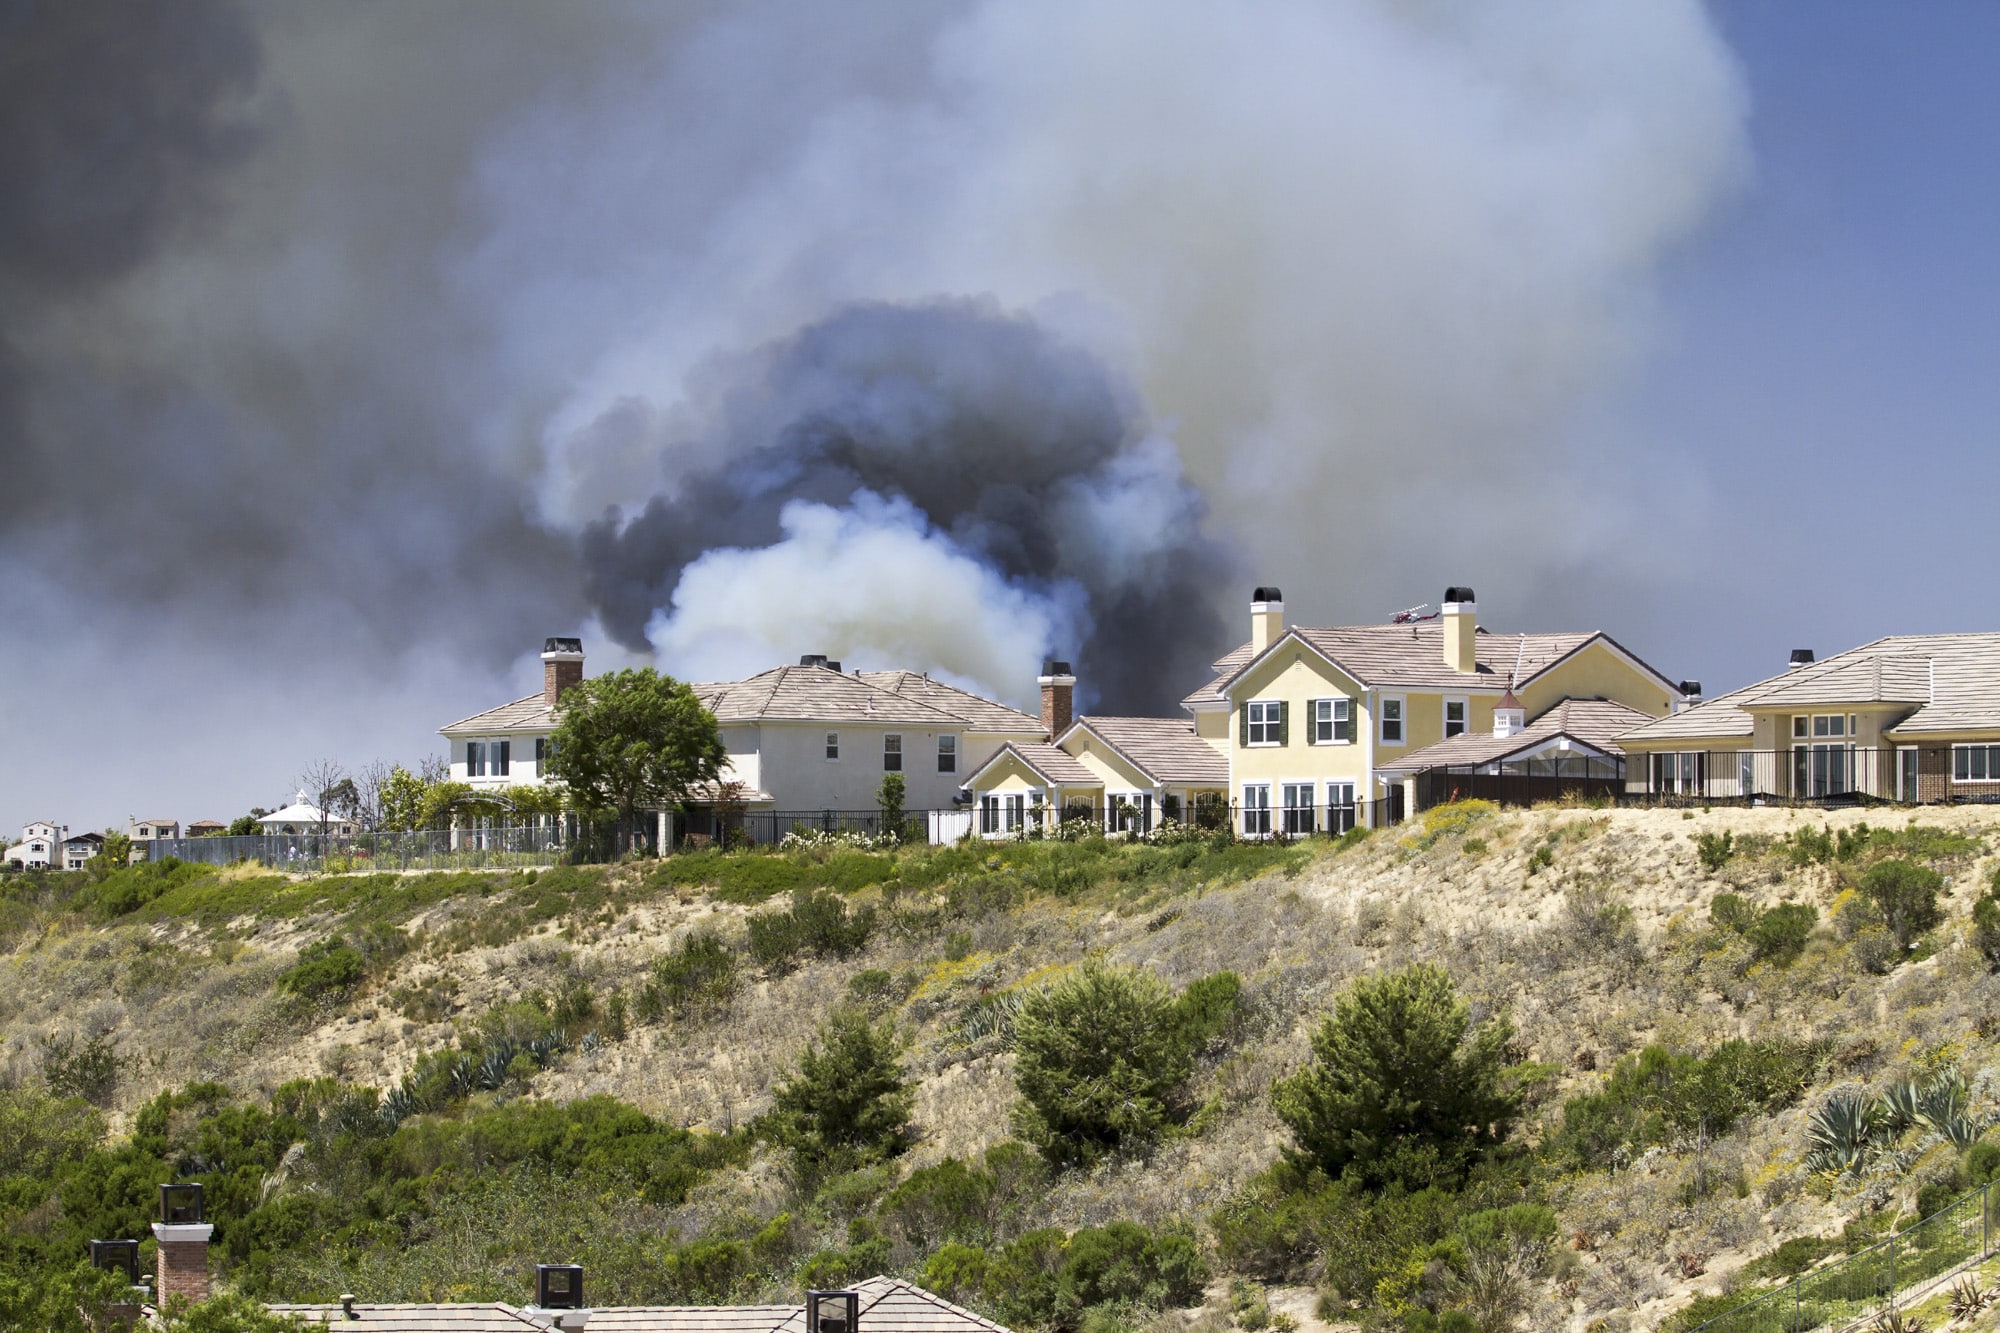
On October 20, 1991, the Oakland/Berkeley Hills fire burned over 1,600 acres, killed 25 people and destroyed nearly 2,449 single-family dwellings and 437 apartment and condominium units, with damage estimated at $1.5 billion (NFPA fire report, published by Cal OES). That history is why we read every estimate for a hill property line by line against what a rebuild on that lot will actually take.
Record rain on New Year’s Eve 2022
Oakland Airport recorded 5.01 inches of rain on December 31, 2022, against a previous daily record of 1.60 inches set in 2005 (NOAA California Nevada River Forecast Center). Over the storms from late December 2022 to mid-January 2023, Oakland set its own 23-day rainfall record of 18.33 inches (National Weather Service). Storms on that scale are why we photograph and record where water came in before anything is dried out or torn out.

Water damage claims in Oakland
Hillside properties face water arriving from uphill: saturated slopes, overwhelmed drainage, and runoff finding its way under foundations. Down in the flats the pattern is different, dominated by aging supply lines, sewer backups, and roofs that have simply run out of years.
Our Expertise: We separate what a policy treats as surface water from what it treats as sudden discharge, because that single distinction decides whether an Oakland water claim gets paid or denied.
The Hidden Risk: Homes on post-and-beam or cripple-wall foundations hide damage in areas nobody inspects. We get under the structure instead of estimating from the living room.

Storm and wind damage claims in Oakland
The hills funnel wind, and autumn offshore events bring dry gusts that push over eucalyptus and pine. Winter fronts arrive from the opposite direction with rain behind them. Both take out roofs, fences, retaining walls, and power service masts.
The Accurate Advantage: We assess the whole envelope, including hillside decks, retaining structures, and drainage that a standard roof-only inspection ignores completely.
Wind and Rain Impact: Wind that lifts roofing lets the following storm inside. We connect those events so interior damage is paid under the loss that actually caused it.
Fire damage claims in Oakland
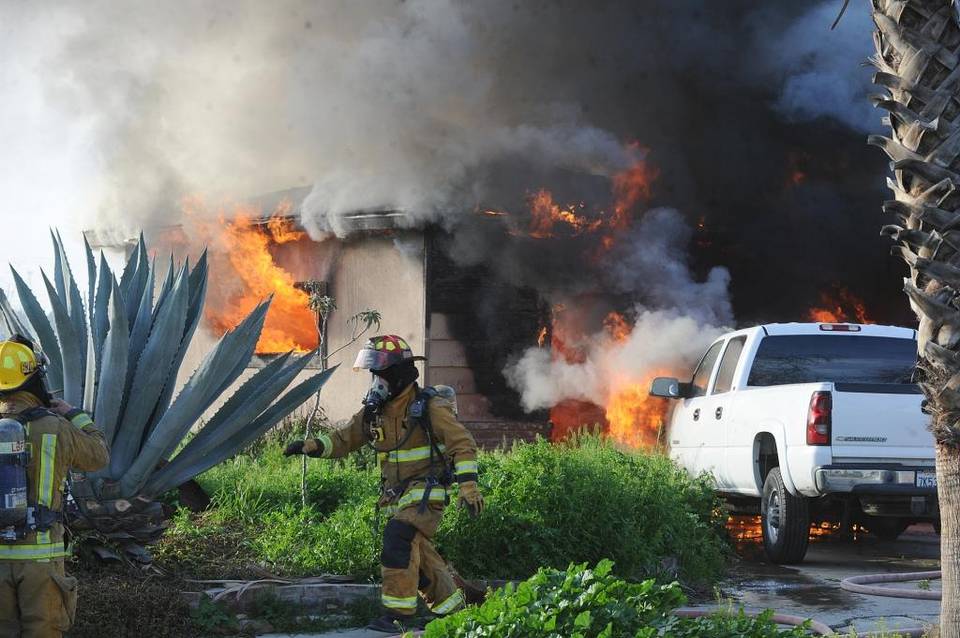
Fire claims here span everything from a kitchen fire in a Craftsman bungalow to a multi-unit loss in a converted building. Older wiring, shared attics, and dense construction all widen the damage well past the room of origin.
What We Do: We inventory contents thoroughly, bring in structural and electrical expertise to find heat-compromised assemblies, and document the smoke and water damage that spreads through the rest of the building.
Code Compliance: Repairs must meet the current California Building Standards Code and City of Oakland permitting. On pre-code housing that often means foundation, electrical, or egress upgrades, and Ordinance or Law coverage is what pays for them when it is properly invoked.
Wildfire and smoke damage claims in Oakland
The Oakland hills are a wildland urban interface in the fullest sense: steep terrain, heavy fuel loads, and homes with limited access. Ember exposure, radiant heat, and dense smoke are realistic outcomes for hill properties, and smoke alone travels citywide.
Smoke and Ash Are Real Damage: Soot penetrates insulation, ductwork, and porous surfaces. A wipe-down is not remediation, and we document contamination well enough that the scope reflects what actually happened.
Access and Debris Costs: After a hill fire, debris removal, slope stabilization, and restricted site access all add real cost. Those items belong in the claim and are frequently missing from a first estimate.
Why Oakland owners choose Accurate Claims Consulting
- Local Cost Insight: Hillside access, crane and shoring needs, and Alameda County labor rates push Oakland repair costs above what standard estimating databases assume.
- Expert Negotiation: We know the levers carriers pull to shrink a number, and we respond with evidence instead of frustration.
- Contingency-Based Service: Nothing is owed for the initial inspection or the policy review. We are paid out of what we recover.
- Full Claim Management: From first notice through the final supplement, the paperwork and the deadlines are ours to carry.
How we handle your claim
- Inspect and document. We inspect the property, including areas under the structure, and document the full loss.
- Estimate and file. We price the repairs at what the work costs in Oakland and Alameda County, then prepare the claim.
- Negotiate and settle. We negotiate with your insurer until the claim is resolved. We only get paid when your insurance company pays the claim.
Public adjusters in California are licensed by the California Department of Insurance, which also helps consumers with claim questions and complaints. For background on the profession, the National Association of Public Insurance Adjusters (NAPIA) is an industry resource.
Claims we handle in Oakland
Every claim below is handled by the same team that works your Oakland file, from the first inspection to the final settlement figure.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
Areas we serve near Oakland
Besides Oakland, we represent policyholders in Berkeley, Fremont, Santa Clara, Stockton, Santa Rosa and Elk Grove, and across Northern California.
Oakland claim questions
Can you help with water damage after a heavy Oakland storm?
Yes. After heavy rain we trace the path the water took, whether through a storm-damaged roof or wall, a failed pipe or runoff from uphill, and present the claim under the coverage that matches that cause.
Is slope failure covered after a heavy storm?
Earth movement is excluded under most homeowners policies, even when rain triggered it. Damage from water entering a storm-damaged roof or wall is treated differently. Because those causes often occur together, investigation and documentation decide the outcome.
Does my Oakland policy cover smoke damage if my house never burned?
Smoke is a covered peril under most policies, and physical contamination of a home some distance from a fire can qualify. What carriers dispute is scope, so testing and clear documentation are essential.
The insurer assigned an adjuster. Why hire my own?
Because that adjuster is paid by the insurance company. A public adjuster is retained by you, values the loss on your behalf, and negotiates for your interests only.
Talk to an Oakland public adjuster
Get the claim settlement you deserve. Whether your loss is a hillside water intrusion, a wind-damaged roof in the flats, or a smoke claim after a fire in the hills, an independent read of your policy costs you nothing.
Call us today or send the form to schedule your free, no-obligation Oakland claim inspection. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.