Public adjuster in Sunnyvale, CA for denied or underpaid claims
Accurate Claims Consulting serves Sunnyvale as licensed public adjusters, retained by policyholders rather than insurers. We handle the inspection, the documentation, the estimate and the negotiation, so the outcome rests on evidence instead of on whoever argues hardest. Our fee is contingent: we only get paid when your insurance company pays the claim.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › Sunnyvale
Who we help in Sunnyvale
Sunnyvale is largely a mid-century city. Ranch tracts and Eichler neighborhoods with flat roofs, radiant floor heating, and floor-to-ceiling glass sit alongside newer townhome developments and a large base of commercial and research property. Each of those building types produces a distinctive kind of insurance claim.
- Owners of Eichler homes and mid-century ranch houses in Sunnyvale tracts
- Townhome and condominium owners in the newer Sunnyvale developments
- Owners and tenants of Sunnyvale commercial and research buildings
Bring us a Sunnyvale claim whenever it needs help: before you file, while it sits in review, after a short payment or after a denial.
Reviews and settlement results


I felt like there was mutual respect between Accurate Claims and my insurance company the whole way.
Mike Hawley, Google review
- Ice maker line leak, Los Angeles, CA (August 2022). The insurer was in the process of denying the leak as long-term damage. Accurate secured a $246,021 settlement. Los Angeles ice maker leak case
- Commercial electrical fire, San Diego, CA (January 2021). A total loss to a 12,000 sq ft commercial building and its contents. The insurer offered only $250,000; Accurate secured a $741,000 settlement. San Diego commercial fire case
Accurate Claims Consulting represents the policyholder only. The adjusters on a Sunnyvale claim learned how carriers evaluate losses while working at Farmers, State Farm and Allstate. Read more on our recent projects and reviews pages.
Sunnyvale flood channels and planning
Sunnyvale flood history is kept by Valley Water and in the city hazard planning record. Three points from those sources matter when a Sunnyvale claim involves water.
Five flood years on the Sunnyvale channels
Valley Water records that the area served by the Sunnyvale East and West channels flooded during major storms in 1963, 1968, 1983, 1986 and 1998 (Valley Water, Sunnyvale East and West Channels Flood Protection).
1,618 parcels waiting on 1% flood protection
Upgrading about 6.4 miles of the Sunnyvale East Channel is designed to give 1,618 parcels protection from a 1% (100-year) flood, and about three miles of West Channel work protects 47 acres of industrial land. Valley Water now anticipates completion by 2032, so until then water that overtops a channel stays a flood-policy matter.
A hazard plan adopted in November 2017
Sunnyvale City Council adopted its annex to the Santa Clara County hazard mitigation plan on November 28, 2017; the plan covers dam failure, drought, earthquake, flood, landslide, severe weather, tsunami and wildfire (City of Sunnyvale, File 17-1030). Sunnyvale is also a planning partner in the 2024 county update that FEMA approved in February 2024 (Santa Clara County OEM).

Water damage claims in Sunnyvale
Flat and low-slope roofs are common here and they are unforgiving. Ponding, failed seams, and clogged drains send water into ceilings during winter storms. Underground radiant heating loops and original copper supply lines add a second category of loss that stays hidden until damage is extensive.
Our Expertise: A radiant slab leak is not a routine plumbing claim. Locating it, documenting the damage to flooring and slab, and scoping the repair correctly requires evidence a standard adjuster visit does not gather.
The Hidden Risk: An insurer may pay for the visible ceiling and leave out the insulation and framing above it. In a flat roof assembly that trapped moisture has nowhere to go.

Storm and wind damage claims in Sunnyvale
Winter gusts sweep across the flat valley floor and lift roofing material at the edges, where flat and low-slope assemblies are most vulnerable. Fencing, mature landscaping, and rooftop equipment take the rest of the damage.
The Accurate Advantage: We measure and photograph the whole roof assembly, including membrane seams, edge metal, and penetrations, since a failure can start at a detail rather than in the field of the roof.
Wind and Rain Impact: A lifted edge admits water at every subsequent storm. Documenting the initiating event prevents the resulting interior damage from being written off as deferred maintenance.
Fire damage claims in Sunnyvale
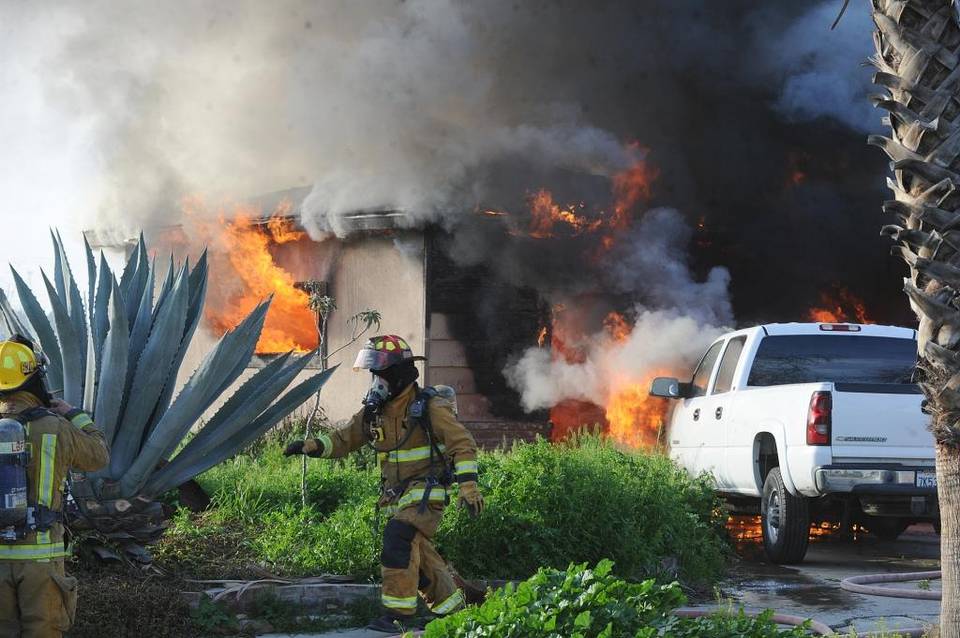
Open floor plans and post-and-beam construction let smoke and heat move through a house quickly, and in commercial and research buildings a small fire can affect sensitive equipment far from the flames.
What We Do: We inventory contents and equipment carefully, bring in specialists to assess heat-affected structure and systems, and pursue business interruption coverage where a commercial policy provides it.
Code Compliance: Rebuilding must meet the current California Building Standards Code and City of Sunnyvale permitting, and mid-century construction can trigger required upgrades. Ordinance or Law coverage is designed to pay for that difference.
Wildfire and smoke damage claims in Sunnyvale
No wildland borders Sunnyvale, but smoke from fires in the Santa Cruz Mountains, the Diablo Range, and the Sierra can reach the valley floor and linger under inversion conditions. Older single-pane glazing and continuously operating ventilation systems both let ash inside.
Smoke and Ash Are Real Damage: Particulate in ductwork, insulation, and soft goods is a covered physical loss when it is documented. Without testing, a carrier may treat it as housekeeping.
Equipment and Inventory: For businesses, ash reaching sensitive equipment or stored product can cause losses that are invisible on a walkthrough. Those exposures need to be established before a file is closed.
What Sunnyvale owners get from Accurate Claims Consulting
- Local Cost Insight: Repairing Eichler and mid-century detailing, and building anywhere in this market, costs well beyond what generic estimating databases assume.
- Expert Negotiation: We show carriers precisely where their scope falls short instead of arguing about it in the abstract.
- Contingency-Based Service: Your first inspection and policy review are free, and we are compensated only from a recovery.
- Full Claim Management: We prepare and submit the Proof of Loss, manage supplements, and track every deadline in the policy.
Our three steps on a Sunnyvale claim
- Inspect and document. We check flat-roof seams, drains and edge metal, trace radiant-slab and supply-line leaks, and test ductwork for ash.
- Estimate and file. We price the work with Santa Clara County construction costs and City of Sunnyvale permit requirements, then file it with the evidence.
- Negotiate and settle. We press the carrier item by item until it pays what the policy owes. We only get paid when your insurance company pays the claim.
The California Department of Insurance licenses public adjusters in this state and runs consumer services for policyholders with claim disputes. If you want to read more about the profession, the National Association of Public Insurance Adjusters (NAPIA) is an industry resource.
Sunnyvale claim types
Choose the claim type closest to your Sunnyvale loss; each page covers what we document and what you should keep.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
Nearby cities we cover
Sunnyvale is one of several Northern California cities we cover, along with San Jose, San Francisco, Concord, Vallejo, Roseville and Redding. See the Northern California service area for the rest.
Sunnyvale claim questions
Is a leak in my radiant heating system covered?
Often the resulting damage is covered even where the failed component is excluded, and the cost of reaching the loop can be payable as well. The distinction is technical, which is why these claims need careful documentation.
My flat roof leaks every winter. Will insurance pay?
Only if a covered event caused the damage. Ongoing deterioration is excluded, so the useful question is whether a specific storm damaged the assembly. That is established with inspection evidence and weather records, not with assumptions.
Does my homeowners policy cover water from the Sunnyvale channels?
No. Standard homeowners policies exclude surface flooding, so water that overtops a channel is a flood-insurance claim. Water that enters through a storm-damaged roof or escapes from a supply line is handled under the homeowners policy instead.
The insurer assigned an adjuster. Why hire my own?
Because that adjuster is paid by the insurance company. We work only for you: we inspect the roof, test for moisture and smoke, write our own estimate and negotiate it against theirs.
Talk to a Sunnyvale public adjuster
Get the claim settlement you deserve. Whether it is a radiant slab leak, a flat roof that failed in a storm, or smoke damage after a regional wildfire, we will review your coverage and give you an honest assessment.
Call us today or send the form to arrange a free, no-obligation inspection of your Sunnyvale property. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.