Public adjuster in San Francisco, CA for flats, apartments and storefronts
Accurate Claims Consulting represents San Francisco owners, landlords and business tenants as licensed public adjusters. We handle the claim from the first inspection to the final signature: evidence, policy reading, estimating and negotiation, all on your side. Our fee is contingent and comes only from what your insurance company pays.
Free consultation. Rated 5 stars on Google (37 reviews) and Yelp (6 reviews): read our reviews.
Home › Service areas › California › Northern California › San Francisco
Who we help in San Francisco
Victorian and Edwardian flats stand shoulder to shoulder on San Francisco hillsides, soft-story apartment buildings sit over ground-floor garages, and much of the housing predates modern building codes. Repair costs and code obligations rise quickly here, and carriers rarely point that out.
- Owners of Victorian and Edwardian flats in the Mission, the Haight and Noe Valley
- Landlords of wood-frame apartment buildings in the soft-story program
- Homeowners and condo associations in the Sunset, the Richmond and the Marina
Whether the claim is new, stalled, underpaid or denied, we can step in on a San Francisco loss at any point.
Reviews and settlements


Great communication and attentive! Me and my wife were pleasantly surprised with their ability to overdeliver.. Thank you Accurate Claims.
Carl Buhl, Google review
- Slab leak, North Hollywood, CA (February 2022). A slab leak flooded the downstairs living room and several other rooms. The insurance company gave the owners $3,000 for repairs; we secured an additional $110,000 for repairs, contents and additional living expenses. North Hollywood slab leak case
- Commercial building fire, San Diego, CA (January 2021). An electrical fire caused a total loss to a 12,000 sq ft commercial building. The insurer offered only $250,000; we secured a $741,000 settlement. San Diego commercial fire case
The adjusters who work San Francisco files spent years evaluating losses for Farmers, State Farm and Allstate before they began representing policyholders. See our recent projects and client reviews for more.
What San Francisco records show
Earthquake retrofits, a federally approved hazard plan and a record storm all shape how we prepare a San Francisco claim.
More than 5,000 buildings in the soft-story program
The Mandatory Soft Story Program, signed into law on April 18, 2013, covers wood-frame buildings permitted before January 1, 1978 that have five or more residential units and two or more stories over a basement or underfloor area. More than 5,000 San Francisco buildings are required to take part (City and County of San Francisco, Soft Story Program).
Hazard plan approved by FEMA on August 14, 2025
The city 2025 Hazards and Climate Resilience Plan addresses 13 natural hazards found in San Francisco. The Federal Emergency Management Agency approved it on August 14, 2025 (ONESF, Hazards and Climate Resilience Plan).
5.46 inches downtown on December 31, 2022
On December 31, 2022 the San Francisco Downtown gauge recorded 5.46 inches of rain. The previous record listed for that day was 2.12 inches, set in 2005, over a 102-year period of record (NOAA California Nevada River Forecast Center).

Water damage claims in San Francisco
Wind-driven rain during an atmospheric river is a familiar San Francisco loss. Flat and low-slope roofs pond, parapet flashing fails, and water tracks down a light well or shared wall into two or three units at once. Inside, aging galvanized supply piping in older buildings fails as well.
Our Expertise: We map moisture through shared walls and stacked units, which matters enormously in flats and condominiums where the association policy and the unit owner policy each cover a different slice of the damage.
The Hidden Risk: In lath-and-plaster construction, water hides for weeks behind finishes that look dry. Carriers use that delay to argue neglect. Dated moisture readings and a clear timeline defeat the argument.

Storm and wind damage claims in San Francisco
Winter storms arrive off the Pacific with little to slow them down. Gusts strip roofing membrane, tear gutters and downspouts off Victorians, flatten fencing, and bring mature trees down onto roofs and parked cars in neighborhoods from the Sunset to Bernal Heights.
The Accurate Advantage: We photograph and measure the entire roof assembly, including flashing, parapets, and skylight curbs, because a carrier that sees only one torn section will pay for only one torn section.
Wind and Rain Impact: Storm damage on old buildings is usually cumulative. We establish which storm caused which loss so your claim is not written off as ordinary wear.
Fire damage claims in San Francisco
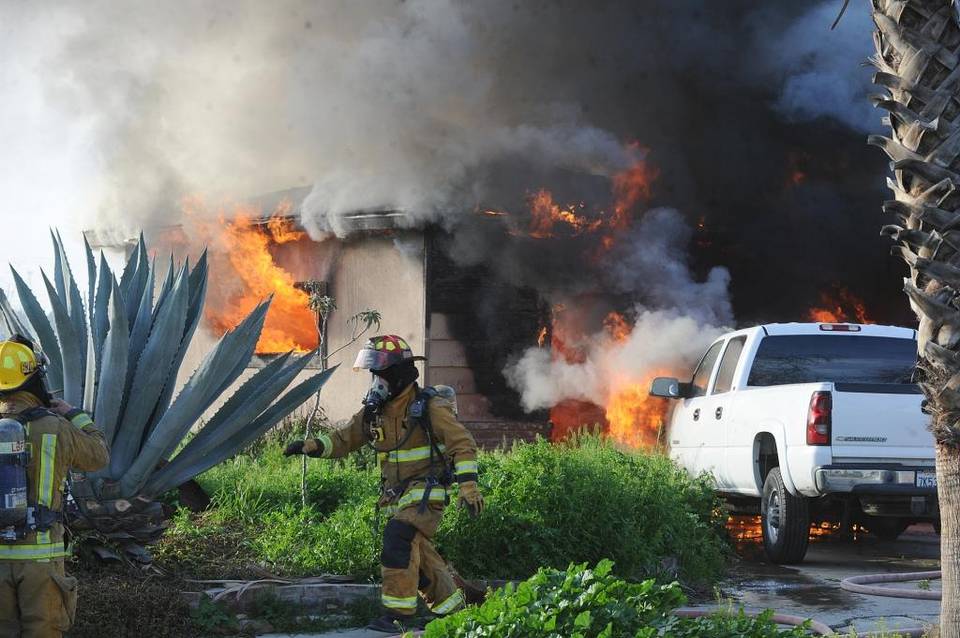
A fire in a San Francisco flat or mixed-use building almost never stays in one unit. Shared walls, common attics, and light wells carry smoke and heat through the structure, and firefighting water reaches floors that never saw flame.
What We Do: We inventory contents unit by unit, coordinate with structural and electrical specialists, and separate what belongs to the building policy from what belongs to your personal or business coverage.
Code Compliance: Rebuilding here means meeting the current California Building Standards Code and San Francisco requirements, and on older buildings that can include seismic and life-safety upgrades. Ordinance or Law coverage exists for exactly this, and we make sure it is applied.
Wildfire smoke and ash claims in San Francisco
San Francisco does not border wildland, but regional wildfire smoke reaches the city regularly, and heavy smoke events push ash into buildings never sealed against it. Original sash windows, roof vents, and commercial HVAC systems running continuously all pull particulate indoors.
Smoke and Ash Are Real Damage: Soot deposits on textiles, ductwork, and stored inventory are a covered loss when the exposure can be shown. Testing and documentation are the difference between a paid claim and a polite denial.
Commercial Exposure: Restaurants, retail, and offices often carry business personal property and spoilage coverage that responds after a smoke event. We read the full policy rather than only the obvious property section.
Why San Francisco owners hire Accurate Claims Consulting
- Local Cost Insight: City construction pricing, permit timelines, and the specialty trades needed for historic detail work all sit far above generic estimating software defaults.
- Expert Negotiation: We answer a low offer with line-item evidence, which is the only thing that reliably moves a carrier position.
- Contingency-Based Service: The first inspection and the policy review are free. Our fee comes out of a recovery, not out of your pocket.
- Full Claim Management: Proof of Loss, supplements, and correspondence are ours to handle so you can get your building and your business back.
How we work a San Francisco claim
- Inspect and document. We go through flats, garages and shared light wells, open lath-and-plaster walls where moisture readings call for it, and photograph roof decks and parapets before repairs begin.
- Estimate and file. We price the work at San Francisco construction rates and Department of Building Inspection permit requirements, including the code upgrades older buildings trigger, then file it with the evidence.
- Negotiate and settle. We keep pressing the carrier, line by line, until the policy pays what it promises. We are paid only when your insurance company pays the claim.
Public adjusters in California hold a license from the California Department of Insurance, whose consumer pages explain how to raise a complaint about the way a claim is handled. The National Association of Public Insurance Adjusters (NAPIA) is an industry resource with background on the profession.
San Francisco claims we handle
Follow a link for how we approach each claim type in San Francisco flats, apartment buildings and storefronts.
- Water damage claims
- Fire damage claims
- Storm damage claims
- Mold damage claims
- Residential property claims
- Commercial property claims
Bay Area cities near San Francisco
Across the bay we also represent owners in Oakland, Berkeley, Hayward and Fremont, and further south in Sunnyvale and San Jose. See the Northern California page for the full list.
San Francisco claim questions
My building is in the soft-story program. Does the retrofit change my claim?
A completed retrofit does not change what the policy covers, but the permit records and engineering plans document the building condition and its upgrades, which helps when a loss is valued. Keep them with your policy. Standard property policies also exclude earthquake damage unless you carry separate earthquake coverage, so check which policy you have.
My building has an association. Whose policy pays?
Often both. The association master policy generally covers the structure and common areas, while your individual policy covers interior finishes, improvements, and personal property. The dividing line lives in the governing documents and the policy language, and we read both before anything is filed.
Does my policy cover wind-driven rain through the roof?
Typically yes, when wind or storm damage created the opening. Long-term roof deterioration is a separate matter and is usually excluded, so the origin of that opening has to be established early and documented properly.
Can I still use a public adjuster if I already filed the claim myself?
Yes. Owners bring us in at every stage, including after an inspection has happened or an offer has been made. Nothing prevents you from having your own representative once a claim is open.
Talk to a San Francisco public adjuster
Get the claim settlement you deserve. A water loss in a Victorian flat, wind damage to a roof deck or a fire claim that has stalled: an independent review of your coverage costs nothing.
Call us or send the form to set up a free San Francisco claim inspection, with no obligation. Office: 12400 Ventura Blvd Suite 1002, Studio City, CA 91604.